HB 1410: RELATING TO HOUSING.
- Session Year: 2025-2026
- House: House
- Latest Version Date: 2025-02-13
Current Status:
Failed
(2026-02-02: Re-Referred to HOU/WLA, WAM.)
Introduced
In Committee
First Chamber
In Committee
Second Chamber
Final Decking
Enacted
Establishes the Supportive Housing Special Fund. Restructures the conveyance tax to a marginal rate system and adjusts the tax for multifamily properties to reflect value on a per-unit basis. Allocates revenues from conveyance tax collections to the Supportive Housing Special Fund. Allocates a portion of conveyance tax collections to the Dwelling Unit Revolving Fund to fund infrastructure programs in county-designated transit-oriented development areas that meet minimum standards of transit-supportive density. Effective 7/1/3000. (HD2)
Establishes the Supportive Housing Special Fund. Restructures the conveyance tax to a marginal rate system and adjusts the tax for multifamily properties to reflect value on a per-unit basis. Allocates revenues from conveyance tax collections to the Supportive Housing Special Fund. Allocates a portion of conveyance tax collections to the Dwelling Unit Revolving Fund to fund infrastructure programs in county-designated transit-oriented development areas that meet minimum standards of transit-supportive density. Effective 7/1/3000. (HD1)
Establishes the Supportive Housing Special Fund. Restructures the conveyance tax to a marginal rate system and adjusts the tax for multifamily properties to reflect value on a per-unit basis. Allocates revenues from conveyance tax collections to the Supportive Housing Special Fund. Allocates a portion of conveyance tax collections to the Dwelling Unit Revolving Fund to fund infrastructure programs in county-designated transit-oriented development areas that meet minimum standards of transit-supportive density.
|
HOUSE OF REPRESENTATIVES |
H.B. NO. |
1410 |
|
THIRTY-THIRD LEGISLATURE, 2025 |
H.D. 2 |
|
|
STATE OF HAWAII |
|
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
RELATING TO HOUSING.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
SECTION 1. The legislature finds that the Hawaii transit-oriented development strategic plan highlights a lack of infrastructure necessary to support affordable housing and mixed-use development near transit. Furthermore, the transit-oriented development infrastructure and finance delivery strategy (2023), developed by the office of planning and sustainable development, identifies the current fragmented infrastructure funding process as a source of inequitable outcomes. The first recommendation of the report is to increase the conveyance tax on high-value, non-owner-occupied homes and allocate a portion of the revenue to finance infrastructure in transit-oriented development zones.
The legislature further finds that there is a need to provide a dedicated funding source to support housing designed for individuals with special needs, including those with alcohol or drug addictions, individuals transitioning from incarceration, youth aging out of foster care, survivors of domestic violence, veterans, individuals with disabilities or mental illness, frail elderly, and chronically homeless individuals. Although significant resources are allocated annually for supportive housing, reliance on legislative appropriations creates uncertainty for non-profit providers and the counties, which face significant risks in developing permanent supportive housing.
The legislature also finds that the conveyance tax, a one-time tax levied at the time of property conveyances, is identified as an appropriate revenue source for affordable housing, infrastructure, land conservation, and homeless services. Despite dramatic increases in housing prices over the past thirteen years, the conveyance tax rates have not been updated since Act 59, Session Laws of Hawaii 2009. In fact, Hawaii's conveyance tax remains significantly lower than comparable high-cost areas in the nation.
The legislature recognizes that without reform, the current conveyance tax rate structure could disproportionately affect affordable multifamily housing, as high total property values for these complexes do not reflect the lower per-unit costs. High conveyance taxes on these properties could be passed on to renters. Moreover, the current rate structure may create market inequities, where even small increases in property value could result in disproportionate tax burdens. Because the property values upon which the conveyance tax is imposed are not tied to inflation, rising home prices will eventually push moderately priced homes into higher tax brackets, compounding the issue.
Accordingly, the purpose of this Act is to:
(1) Restructure the conveyance tax to a marginal rate system, applying higher rates only to property values exceeding specified thresholds;
(2) Adjust the conveyance tax for multifamily properties to reflect value on a per-unit basis;
(3) Increase conveyance tax revenue by approximately thirty per cent, generating an estimated $35,000,000 annually, by:
(A) Raising the tax rate on non-owner-occupied homes valued at over $2,000,000;
(B) Slightly increasing the tax rate on owner-occupied homes valued at over $6,000,000; and
(C) Ensuring revenue neutrality for owner-occupied homes valued at $6,000,000 and under and non-owner-occupied homes valued at $2,000,000 and under through the adjusted marginal rate structure;
(4) Tie conveyance tax rates to a cost-of-living adjustment to maintain equity over time; and
(5) Allocate a portion of the additional revenue to permanent supportive housing and infrastructure in transit-oriented development zones.
SECTION 2. Chapter 201H, Hawaii Revised Statutes, is amended by adding a new subpart to part III to be appropriately designated and to read as follows:
" . Supportive Housing Special Fund
§201H-A Supportive housing special fund. (a) There is established a supportive housing special fund to be administered by the corporation for the purpose of developing, operating, and maintaining affordable, permanent housing and the provision of supportive services for individuals or families with special needs.
(b) Moneys in the fund may be used to:
(1) Make loans to finance the development, pre-development, construction, acquisition, preservation, or substantial rehabilitation of supportive housing projects;
(2) Make project-based rental assistance payments;
(3) Make payments for supportive services for households residing in the supportive housing projects; and
(4) For other housing services or activities as provided in rules adopted by the corporation without regard to chapter 91.
(c) The fund may include sums appropriated by the legislature, private contributions, proceeds from repayment of loans, interest, fees, other returns, and moneys from other sources.
(d) An amount from the fund, to be set by the corporation and authorized by the legislature, may be used for administrative expenses incurred by the corporation in administering the fund; provided that moneys in the fund shall not be used to finance day-to-day administrative expenses of the projects allotted moneys from the fund.
(e) The corporation shall consult with the counties and community-based organizations to leverage funds and obtain input on selection of projects.
(f) The corporation may contract with other executive branch departments or agencies, the counties, or private or nonprofit organizations as necessary for the provision of supportive housing and services. The corporation shall be exempt from chapter 103D in selecting a qualified private or nonprofit organization to assist with the development and maintenance of supportive housing and provision of rental assistance and supportive services. The corporation may, without regard to chapter 91, establish rules and qualification standards for participants of the supportive housing program.
(g) The corporation may establish, revise, charge, and collect a reasonable service fee, as necessary, in connection with its financing, services, and approvals under this subpart. The fees shall be deposited into the supportive housing special fund.
(h) The corporation shall submit a report to the legislature no later than twenty days prior to the convening of each regular session describing the projects funded using moneys from the supportive housing special fund.
§201H-B Additional powers. The powers conferred upon the corporation by this subpart shall be in addition and supplemental to the powers conferred by any other law, and nothing in this subpart shall be construed as limiting any powers, rights, privileges, or immunities conferred."
SECTION 3. Section 201H-191, Hawaii Revised Statutes, is amended to read as follows:
"§201H-191 Dwelling unit
revolving fund. (a) There is created a dwelling unit revolving
fund. The funds appropriated for the
purpose of the dwelling unit revolving fund [and], conveyance taxes
received pursuant to section 247-7(4), and all moneys received or collected
by the corporation for the purpose of the revolving fund shall be deposited in
the revolving fund. The proceeds in the
revolving fund shall be used [to reimburse]:
(1) To reimburse
the general fund to pay the interest on general obligation bonds issued for the
purposes of the revolving fund[, for the];
(2) For
necessary expenses in administering housing development programs and regional
state infrastructure programs[, and for carrying];
(3) To carry
out the purposes of housing development programs and regional state
infrastructure programs, including but not limited to the expansion of
community facilities and regional state infrastructure constructed in
conjunction with housing and mixed-use transit-oriented development projects,
permanent primary or secondary financing, and supplementing building costs,
federal guarantees required for operational losses[, and all];
(4) To fund infrastructure programs in areas that meet transit-supportive density requirements; provided that proceeds from the conveyance tax deposited pursuant to section 247-7(4) shall only be used for the purposes of this paragraph; and
(5) All things required by any federal agency in the construction and receipt of federal funds or low‑income housing tax credits for housing projects.
(b) Subject to the requirements of subsection (a), proceeds in the revolving fund may be used to establish and operate regional state infrastructure subaccounts pursuant to section 201H-191.5.
(c) For purposes of this section:
"County-designated transit-oriented development area" means a geographic area designated by a county for transit-oriented development by an adopted ordinance, plan, or resolution. These areas shall generally consist of lands within a one-half-mile radius of a transit hub or transit station but may extend further when there is state and county agreement about the extent of the transit-oriented development area.
"Floor area ratio" means the quotient, expressed as a decimal number, that results from dividing a structure's total floor area by the total area of the lot or parcel on which the structure is located.
"Ministerial permit" means a permit processed based upon standards established through county ordinance or rule and issued by the director of the county agency responsible for land use or a single county officer designated by ordinance.
"Transit-supportive density requirements" means a county-designated transit-oriented development area:
(1) With development standards that allow a floor area ratio of at least:
(A) 4.0 for all uses that are permitted in a county-designated transit-oriented development area or by the underlying county zoning;
(B) 6.0 for all uses that are permitted in a county-designated transit-oriented development area within one-half mile of a station of a locally preferred alternative for a mass transit project; and
(C) For all uses that are permitted within one-quarter mile of a station of a locally preferred alternative for a mass transit project, whichever is greater:
(i) 7.0;
(ii) The maximum floor area ratio allowed by the adopted transit-oriented development special district; or
(iii) The maximum floor area ratio allowed by the applicable transit-oriented development plan;
(2) For which permits for development are processed as a ministerial permit subject to applicable objective design standards;
(3) Where there is no imposition of a development standard that renders it impracticable to build a usable structure for the permitted uses at the applicable transit-supportive density; and
(4) Where funds collected pursuant to section 46-16.8 have been expended in the county-designated transit-oriented development area in which the development is located."
SECTION 4. Section 247-2, Hawaii Revised Statutes, is amended to read as follows:
"§247-2 Basis and rate of tax. (a) The tax imposed by section 247-1 shall be based on the actual and full consideration (whether cash or otherwise, including any promise, act, forbearance, property interest, value, gain, advantage, benefit, or profit), paid or to be paid for all transfers or conveyance of realty or any interest therein, that shall include any liens or encumbrances thereon at the time of sale, lease, sublease, assignment, transfer, or conveyance, and shall be at the following rates:
(1) Except as provided in paragraph (2):
(A) [Ten cents per
$100 for] For properties with a value of less than $600,000[;]: 10 cents per $100;
(B) [Twenty cents
per $100 for] For properties with a value of at least $600,000, but
less than $1,000,000[;]: $600
plus 35 cents per $100 of excess over $600,000;
(C) [Thirty
cents per $100 for] For properties with a value of at least
$1,000,000, but less than $2,000,000[;]: $2,000 plus 60 cents per $100 of excess over
$1,000,000;
(D) [Fifty
cents per $100 for] For properties with a value of at least
$2,000,000, but less than $4,000,000[;]: $8,000 plus 85 cents per $100 of excess over
$2,000,000;
(E) [Seventy
cents per $100 for] For properties with a value of at least
$4,000,000, but less than $6,000,000[;]: $25,000 plus $1.20 per $100 of excess over
$4,000,000;
(F) [Ninety
cents per $100 for] For properties with a value of at least
$6,000,000, but less than $10,000,000[; and]: $49,000 plus $1.75 per $100 of excess over
$6,000,000; and
(G) [One
dollar per $100 for] For properties with a value of at least
$10,000,000 [or greater; and]: $119,000 plus $3 per $100 of excess over
$10,000,000; and
(2) For the sale of a
condominium [or], single family residence, or land zoned
agricultural with a residential dwelling unit, for which the purchaser is
ineligible for a county homeowner's exemption on property tax:
(A) [Fifteen cents
per $100 for] For properties with a value of less than $600,000[;]: 15 cents per $100;
(B) [Twenty-five
cents per $100 for] For properties with a value of at least
$600,000, but less than $1,000,000[;]: $900 plus 40 cents per $100 of excess over
$600,000;
(C) [Forty
cents per $100 for] For properties with a value of at least
$1,000,000, but less than $2,000,000[;]: $2,500 plus 65 cents per $100 of excess over
$1,000,000;
(D) [Sixty
cents per $100 for] For properties with a value of at least
$2,000,000, but less than $4,000,000[;]: $9,000 plus $2.00 per $100 of excess over
$2,000,000;
(E) [Eighty-five
cents per $100 for] For properties with a value of at least
$4,000,000, but less than $6,000,000[;]: $49,000 plus $2.50 per $100 of excess over
$4,000,000;
(F) [One
dollar and ten cents per $100 for] For properties with a value of at
least $6,000,000, but less than $10,000,000[; and]: $99,000 plus $3.25 per $100 of excess over
$6,000,000; and
(G) [One
dollar and twenty-five cents per $100 for] For properties with a
value of $10,000,000 or greater[,]:
$229,000 plus $4.10 per $100 of excess over $10,000,000,
of [such] the actual and full
consideration; provided that in the case of a lease or sublease, this chapter
shall apply only to a lease or sublease whose full unexpired term is for a
period of five years or more[, and in those cases, including (where
appropriate) those cases where the]; provided further that if a
lease has been extended or amended, the tax in this chapter shall be based on
the cash value of the lease rentals discounted to present day value and
capitalized at the rate of six per cent, plus the actual and full consideration
paid or to be paid for any and all improvements, if any, that shall include
on-site as well as off-site improvements, applicable to the leased premises;
and provided further that the tax imposed for each transaction shall be [not]
no less than $1.
The rates in this section shall apply to the transfer or conveyance of a multifamily residential property; provided that "value", for purposes of determining the applicable rate, shall be an amount calculated by dividing the actual and full consideration for the transfer or conveyance of realty or any interest therein by the number of residential dwelling units in the property. As used in this subsection, "multifamily residential property" means a structure that is located within the state urban land use district and divided into five or more dwelling units.
(b) For each taxable year beginning after December 31, 2025, the director of taxation, no later than December 15 of the preceding calendar year, shall recompute the rates in subsection (a) by multiplying the dollar amount for the preceding taxable year by the cost-of-living adjustment factor, if the cost-of-living adjustment factor is greater than 1.0, and rounding off the resulting product to the nearest $1; provided that if the cost-of-living adjustment factor is less than or equal to 1.0 in a given year, then no adjustment shall occur in the following year.
As used in this subsection, "cost-of-living adjustment factor" means a factor calculated by adding 1.0 to the quotient of the percentage change in the Urban Hawaii Consumer Price Index for all items divided by one hundred, as published by the United States Department of Labor, from July of the preceding calendar year to July of the current calendar year; provided that if the Urban Hawaii Consumer Price Index is discontinued, the Chained Consumer Price Index for All Urban Consumers, as published by the United States Department of Labor, shall be used to calculate the cost-of-living adjustment factor."
SECTION 5. Section 247-7, Hawaii Revised Statutes, is amended to read as follows:
"§247-7 Disposition of taxes. All taxes collected under this chapter shall be paid into the state treasury to the credit of the general fund of the State, to be used and expended for the purposes for which the general fund was created and exists by law; provided that of the taxes collected each fiscal year:
(1) [Ten]
Eight per cent or [$5,100,000,] $10,000,000, whichever
is less, shall be paid into the land conservation fund established pursuant to
section 173A-5; [and]
(2) [Fifty]
Thirty-eight per cent or [$38,000,000,] $50,000,000,
whichever is less, shall be paid into the rental housing revolving fund
established by section 201H-202[.];
(3) Eight per cent or $10,000,000, whichever is less, shall be paid into the supportive housing special fund established pursuant to section 201H-A; and
(4) Ten per cent shall be paid into the dwelling unit revolving fund established pursuant to section 201H-191."
SECTION 6. This Act does not affect rights and duties that matured, penalties that were incurred, and proceedings that were begun before its effective date.
SECTION 7. In codifying the new sections added by section 2 of this Act, the revisor of statutes shall substitute appropriate section numbers for the letters used in designating the new sections in this Act.
SECTION 8. Statutory material to be repealed is bracketed and stricken. New statutory material is underscored.
SECTION 9. This Act shall take effect on July 1, 3000.
Report Title:
Conveyance Tax; Supportive Housing Special Fund; Dwelling Unit Revolving Fund; Infrastructure Funding; County-designated Transit-oriented Development
Description:
Establishes the Supportive Housing Special Fund. Restructures the conveyance tax to a marginal rate system and adjusts the tax for multifamily properties to reflect value on a per-unit basis. Allocates revenues from conveyance tax collections to the Supportive Housing Special Fund. Allocates a portion of conveyance tax collections to the Dwelling Unit Revolving Fund to fund infrastructure programs in county-designated transit-oriented development areas that meet minimum standards of transit-supportive density. Effective 7/1/3000. (HD2)
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
HOUSE OF REPRESENTATIVES |
H.B. NO. |
1410 |
|
THIRTY-THIRD LEGISLATURE, 2025 |
H.D. 1 |
|
|
STATE OF HAWAII |
|
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
RELATING TO HOUSING.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
SECTION 1. The legislature finds that the Hawaii transit-oriented development strategic plan highlights a lack of infrastructure necessary to support affordable housing and mixed-use development near transit. Furthermore, the transit-oriented development infrastructure and finance delivery strategy (2023), developed by the office of planning and sustainable development, identifies the current fragmented infrastructure funding process as a source of inequitable outcomes. The first recommendation of the report is to increase the conveyance tax on high-value, non-owner-occupied homes and allocate a portion of the revenue to finance infrastructure in transit-oriented development zones.
The legislature further finds that there is a need to provide a dedicated funding source to support housing designed for individuals with special needs, including those with alcohol or drug addictions, individuals transitioning from incarceration, youth aging out of foster care, survivors of domestic violence, veterans, individuals with disabilities or mental illness, frail elderly, and chronically homeless individuals. Although significant resources are allocated annually for supportive housing, reliance on legislative appropriations creates uncertainty for non-profit providers and the counties, which face significant risks in developing permanent supportive housing.
The legislature also finds that the conveyance tax, a one-time tax levied at the time of property sales, is identified as an appropriate revenue source for affordable housing, infrastructure, land conservation, and homeless services. Despite dramatic increases in housing prices over the past thirteen years, the conveyance tax rates have not been updated since Act 59, Session Laws of Hawaii 2009. In fact, Hawaii's conveyance tax remains significantly lower than comparable high-cost areas in the nation.
The legislature recognizes that without reform, the current conveyance tax rate structure could disproportionately affect affordable multifamily housing, as high total property values for these complexes do not reflect the lower per-unit costs. High conveyance taxes on these properties could be passed on to renters. Moreover, the current rate structure may create market inequities, where even small increases in property value could result in disproportionate tax burdens. Because the conveyance tax is not tied to inflation, rising home prices will eventually push moderately priced homes into higher tax brackets, compounding the issue.
Accordingly, the purpose of this Act is to:
(1) Restructure the conveyance tax to a marginal rate system, applying higher rates only to property values exceeding specified thresholds;
(2) Adjust the conveyance tax for multifamily properties to reflect value on a per-unit basis;
(3) Increase conveyance tax revenue by approximately thirty per cent, generating an estimated $35,000,000 annually, by:
(A) Raising the tax rate on non-owner-occupied homes valued at over $2,000,000;
(B) Slightly increasing the tax rate on owner-occupied homes valued at over $6,000,000; and
(C) Ensuring revenue neutrality for owner-occupied homes valued at $6,000,000 and under and non-owner-occupied homes valued at $2,000,000 and under through the adjusted marginal rate structure;
(4) Tie conveyance tax rates to a cost-of-living adjustment to maintain equity over time; and
(5) Allocate a portion of the additional revenue to permanent supportive housing and infrastructure in transit-oriented development zones.
SECTION 2. Chapter 201H, Hawaii Revised Statutes, is amended by adding a new subpart to part III to be appropriately designated and to read as follows:
" . Supportive Housing Special Fund
§201H-A Supportive housing special fund. (a) There is established a supportive housing special fund to be administered by the corporation for the purpose of developing, operating, and maintaining affordable, permanent housing and the provision of supportive services for individuals or families with special needs.
(b) Moneys in the fund may be used to:
(1) Make loans to finance the development, pre-development, construction, acquisition, preservation, or substantial rehabilitation of supportive housing projects;
(2) Make project-based rental assistance payments;
(3) Make payments for supportive services for households residing in the supportive housing projects; and
(4) For other housing services or activities as provided in rules adopted by the corporation without regard to chapter 91.
(c) The fund may include sums appropriated by the legislature, private contributions, proceeds from repayment of loans, interest, fees, other returns, and moneys from other sources.
(d) An amount from the fund, to be set by the corporation and authorized by the legislature, may be used for administrative expenses incurred by the corporation in administering the fund; provided that moneys in the fund shall not be used to finance day-to-day administrative expenses of the projects allotted moneys from the fund.
(e) The corporation shall consult with the counties and community-based organizations to leverage funds and obtain input on selection of projects.
(f) The corporation may contract with other executive branch departments or agencies, the counties, or private or nonprofit organizations as necessary for the provision of supportive housing and services. The corporation shall be exempt from chapter 103D in selecting a qualified private or nonprofit organization to assist with the development and maintenance of supportive housing and provision of rental assistance and supportive services. The corporation may, without regard to chapter 91, establish rules and qualification standards for participants of the supportive housing program.
(g) The corporation may establish, revise, charge, and collect a reasonable service fee, as necessary, in connection with its financing, services, and approvals under this subpart. The fees shall be deposited into the supportive housing special fund.
(h) The corporation shall submit a report to the legislature no later than twenty days prior to the convening of each regular session describing the projects funded using moneys from the supportive housing special fund.
§201H-B Additional powers. The powers conferred upon the corporation by this subpart shall be in addition and supplemental to the powers conferred by any other law, and nothing in this subpart shall be construed as limiting any powers, rights, privileges, or immunities conferred."
SECTION 3. Section 201H-191, Hawaii Revised Statutes, is amended to read as follows:
"§201H-191 Dwelling unit revolving fund. (a)
There is created a dwelling unit revolving fund. The funds appropriated for the purpose of the
dwelling unit revolving fund [and], conveyance taxes received
pursuant to section 247-7(4), and all moneys received or collected by the
corporation for the purpose of the revolving fund shall be deposited in the
revolving fund. The proceeds in the
revolving fund shall be used [to reimburse]:
(1) To reimburse
the general fund to pay the interest on general obligation bonds issued for the
purposes of the revolving fund[, for the];
(2) For
necessary expenses in administering housing development programs and regional
state infrastructure programs[, and for carrying];
(3) To carry
out the purposes of housing development programs and regional state
infrastructure programs, including but not limited to the expansion of
community facilities and regional state infrastructure constructed in
conjunction with housing and mixed-use transit-oriented development projects,
permanent primary or secondary financing, and supplementing building costs,
federal guarantees required for operational losses[, and all];
(4) To fund infrastructure programs in areas that meet minimum standards of transit-supportive density requirements; provided that proceeds from the conveyance tax deposited pursuant to section 247-7(4) shall only be used for purposes of this paragraph; and
(5) All things required by any federal agency in the construction and receipt of federal funds or low‑income housing tax credits for housing projects.
(b) Subject to the requirements of subsection (a), proceeds in the revolving fund may be used to establish and operate regional state infrastructure subaccounts pursuant to section 201H-191.5.
(c) For purposes of this section:
"County-designated transit-oriented development area" means a geographic area designated by a county for transit-oriented development by an adopted ordinance, plan, or resolution. These areas shall generally consist of lands within a one-half-mile radius of a transit hub or transit station but may extend further when there is state and county agreement about the extent of the transit-oriented development area.
"Floor area ratio" means the quotient, expressed as a decimal number, that results from dividing a structure's total floor area by the total area of the lot or parcel on which the structure is located.
"Ministerial" means a permit process based upon standards established through county ordinance or rule and issued by the director of the county agency responsible for land use or a single county officer designated by ordinance.
"Transit-supportive density" means a county-designated transit-oriented development area:
(1) With development standards that allow a floor area ratio of at least:
(A) 4.0 for all uses that are permitted in a county-designated transit-oriented development area or by the underlying county zoning;
(B) 6.0 for all uses that are permitted in a county-designated transit-oriented development area within one-half mile of a station of a locally preferred alternative for a mass transit project; and
(C) For all uses that are permitted within one-quarter mile of a station of a locally preferred alternative for a mass transit project, whichever is greater:
(i) 7.0;
(ii) The maximum floor area ratio allowed by the adopted transit-oriented development special district; or
(iii) The maximum floor area ratio allowed by the applicable transit-oriented development plan;
(2) For which permits for development are processed as a ministerial permit subject to applicable objective design standards;
(3) Where there is no imposition of a development standard that renders it impracticable to build a usable structure for the permitted uses at the applicable transit-supportive density; and
(4) Where funds collected pursuant to section 46-16.8 have been expended in the county-designated transit-oriented development area in which the development is located."
SECTION 4. Section 247-2, Hawaii Revised Statutes, is amended to read as follows:
"§247-2 Basis and rate of tax. (a) The tax imposed by section 247-1 shall be based on the actual and full consideration (whether cash or otherwise, including any promise, act, forbearance, property interest, value, gain, advantage, benefit, or profit), paid or to be paid for all transfers or conveyance of realty or any interest therein, that shall include any liens or encumbrances thereon at the time of sale, lease, sublease, assignment, transfer, or conveyance, and shall be at the following rates:
(1) Except as provided in paragraph (2):
(A) [Ten cents per
$100 for] For properties with a value of less than $600,000[;]: 10 cents per $100;
(B) [Twenty cents
per $100 for] For properties with a value of at least $600,000, but
less than $1,000,000[;]: $600
plus 35 cents per $100 of excess over $600,000;
(C) [Thirty
cents per $100 for] For properties with a value of at least
$1,000,000, but less than $2,000,000[;]: $2,000 plus 60 cents per $100 of excess over
$1,000,000;
(D) [Fifty
cents per $100 for] For properties with a value of at least
$2,000,000, but less than $4,000,000[;]: $8,000 plus 85 cents per $100 of excess over
$2,000,000;
(E) [Seventy
cents per $100 for] For properties with a value of at least
$4,000,000, but less than $6,000,000[;]: $25,000 plus $1.20 per $100 of excess over
$4,000,000;
(F) [Ninety
cents per $100 for] For properties with a value of at least
$6,000,000, but less than $10,000,000[; and]: $49,000 plus $1.75 per $100 of excess over
$6,000,000; and
(G) [One
dollar per $100 for] For properties with a value of at least
$10,000,000 [or greater; and]: $119,000 plus $3 per $100 of excess
over $10,000,000; and
(2) For the sale of a condominium or single family residence for which the purchaser is ineligible for a county homeowner's exemption on property tax:
(A) [Fifteen cents
per $100 for] For properties with a value of less than $600,000[;]: 15 cents per $100;
(B) [Twenty-five
cents per $100 for] For properties with a value of at least
$600,000, but less than $1,000,000[;]: $900 plus 40 cents per $100 of excess over
$600,000;
(C) [Forty
cents per $100 for] For properties with a value of at least
$1,000,000, but less than $2,000,000[;]: $2,500 plus 65 cents per $100 of excess over
$1,000,000;
(D) [Sixty
cents per $100 for] For properties with a value of at least
$2,000,000, but less than $4,000,000[;]: $9,000 plus $2.00 per $100 of excess over
$2,000,000;
(E) [Eighty-five
cents per $100 for] For properties with a value of at least
$4,000,000, but less than $6,000,000[;]: $49,000 plus $2.50 per $100 of excess over
$4,000,000;
(F) [One
dollar and ten cents per $100 for] For properties with a value of at
least $6,000,000, but less than $10,000,000[; and]: $99,000 plus $3.25 per $100 of excess over
$6,000,000; and
(G) [One
dollar and twenty-five cents per $100 for] For properties with a
value of $10,000,000 or greater[,]:
$229,000 plus $4.10 per $100 of excess over $10,000,000,
of [such] the actual and full
consideration; provided that in the case of a lease or sublease, this chapter
shall apply only to a lease or sublease whose full unexpired term is for a
period of five years or more[, and in those cases, including (where
appropriate) those cases where the]; provided further that if a
lease has been extended or amended, the tax in this chapter shall be based on
the cash value of the lease rentals discounted to present day value and
capitalized at the rate of six per cent, plus the actual and full consideration
paid or to be paid for any and all improvements, if any, that shall include
on-site as well as off-site improvements, applicable to the leased premises;
and provided further that the tax imposed for each transaction shall be [not]
no less than $1.
The rates in this section shall apply to the transfer or conveyance of a multifamily residential property; provided that "value", for purposes of determining the applicable rate, shall be an amount calculated by dividing the actual and full consideration by the number of residential dwelling units in the property; provided further that the tax shall be calculated by applying the applicable rate to the actual and full consideration for the transfer or conveyance of realty or any interest therein. As used in this subsection, "multifamily residential property" means a structure that is located within the state urban land use district and divided into five or more dwelling units.
(b) For each taxable year beginning after December 31, 2025, the director of taxation, no later than December 15 of the preceding calendar year, shall recompute the rates in subsection (a) by multiplying the dollar amount for the preceding taxable year by the cost-of-living adjustment factor, if the cost-of-living adjustment factor is greater than 1.0, and rounding off the resulting product to the nearest $1; provided that if the cost-of-living adjustment factor is less than or equal to 1.0 in a given year, then no adjustment shall occur in the following year.
As used in this subsection, "cost-of-living adjustment factor" means a factor calculated by adding 1.0 to the quotient of the percentage change in the Urban Hawaii Consumer Price Index for all items divided by one hundred, as published by the United States Department of Labor, from July of the preceding calendar year to July of the current calendar year; provided that if the Urban Hawaii Consumer Price Index is discontinued, the Chained Consumer Price Index for All Urban Consumers, as published by the United States Department of Labor, shall be used to calculate the cost-of-living adjustment factor."
SECTION 5. Section 247-7, Hawaii Revised Statutes, is amended to read as follows:
"§247-7 Disposition of taxes. All taxes collected under this chapter shall be paid into the state treasury to the credit of the general fund of the State, to be used and expended for the purposes for which the general fund was created and exists by law; provided that of the taxes collected each fiscal year:
(1) [Ten]
Eight per cent or [$5,100,000,] $10,000,000, whichever
is less, shall be paid into the land conservation fund established pursuant to
section 173A-5; [and]
(2) [Fifty]
Thirty-eight per cent or [$38,000,000,] $50,000,000,
whichever is less, shall be paid into the rental housing revolving fund
established by section 201H-202[.];
(3) Eight per cent or $10,000,000, whichever is less, shall be paid into the supportive housing special fund established pursuant to section 201H-A; and
(4) Ten per cent shall be paid into the dwelling unit revolving fund established pursuant to section 201H-191."
SECTION 6. This Act does not affect rights and duties that matured, penalties that were incurred, and proceedings that were begun before its effective date.
SECTION 7. In codifying the new sections added by section 2 of this Act, the revisor of statutes shall substitute appropriate section numbers for the letters used in designating the new sections in this Act.
SECTION 8. Statutory material to be repealed is bracketed and stricken. New statutory material is underscored.
SECTION 9. This Act shall take effect on July 1, 3000.
Report Title:
Conveyance Tax; Supportive Housing Special Fund; Dwelling Unit Revolving Fund; Infrastructure Funding; County-designated Transit-oriented Development
Description:
Establishes the Supportive Housing Special Fund. Restructures the conveyance tax to a marginal rate system and adjusts the tax for multifamily properties to reflect value on a per-unit basis. Allocates revenues from conveyance tax collections to the Supportive Housing Special Fund. Allocates a portion of conveyance tax collections to the Dwelling Unit Revolving Fund to fund infrastructure programs in county-designated transit-oriented development areas that meet minimum standards of transit-supportive density. Effective 7/1/3000. (HD1)
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
HOUSE OF REPRESENTATIVES |
H.B. NO. |
1410 |
|
THIRTY-THIRD LEGISLATURE, 2025 |
|
|
|
STATE OF HAWAII |
|
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
relating to housing.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
SECTION 1. The legislature finds that the Hawaii transit-oriented development strategic plan highlights a lack of infrastructure necessary to support affordable housing and mixed-use development near transit. Furthermore, the transit-oriented development infrastructure and finance delivery strategy (2023), developed by the office of planning and sustainable development, identifies the current fragmented infrastructure funding process as a source of inequitable outcomes. The first recommendation of the report is to increase the conveyance tax on high-value, non-owner-occupied homes and allocate a portion of the revenue to finance infrastructure in transit-oriented development zones.
The legislature further finds that there is a need to provide a dedicated funding source to support housing designed for individuals with special needs, including those with alcohol or drug addictions, individuals transitioning from incarceration, youth aging out of foster care, survivors of domestic violence, veterans, individuals with disabilities or mental illness, frail elderly, and chronically homeless individuals. Although significant resources are allocated annually for supportive housing, reliance on legislative appropriations creates uncertainty for non-profit providers and the counties, which face significant risks in developing permanent supportive housing.
The legislature also finds that the conveyance tax, a one-time tax levied at the time of property sales, is identified as an appropriate revenue source for affordable housing, infrastructure, land conservation, and homeless services. Despite dramatic increases in housing prices over the past thirteen years, the conveyance tax rates have not been updated since Act 59, Session Laws of Hawaii 2009. In fact, Hawaii's conveyance tax remains significantly lower than comparable high-cost areas in the nation.
The legislature recognizes that without reform, the current conveyance tax rate structure could disproportionately affect affordable multifamily housing, as high total property values for these complexes do not reflect the lower per-unit costs. High conveyance taxes on these properties could be passed on to renters. Moreover, the current rate structure may create market inequities, where even small increases in property value could result in disproportionate tax burdens. Because the conveyance tax is not tied to inflation, rising home prices will eventually push moderately priced homes into higher tax brackets, compounding the issue.
Accordingly, the purpose of this Act is to:
(1) Restructure the conveyance tax to a marginal rate system, applying higher rates only to property values exceeding specified thresholds;
(2) Adjust the conveyance tax for multifamily properties to reflect value on a per-unit basis;
(3) Increase conveyance tax revenue by approximately thirty per cent, generating an estimated $35,000,000 annually, by:
(A) Raising the tax rate on non-owner-occupied homes valued at over $2,000,000;
(B) Slightly increasing the tax rate on owner-occupied homes valued at over $6,000,000; and
(C) Ensuring revenue neutrality for owner-occupied homes valued at $6,000,000 and under and non-owner-occupied homes valued at $2,000,000 and under through the adjusted marginal rate structure;
(4) Tie conveyance tax rates to a cost-of-living adjustment to maintain equity over time; and
(5) Allocate a portion of the additional revenue to permanent supportive housing and infrastructure in transit-oriented development zones.
SECTION 2. Chapter 201H, Hawaii Revised Statutes, is amended by adding a new subpart to part III to be appropriately designated and to read as follows:
" . Supportive Housing Special Fund
§201H-A Supportive housing special fund. (a) There is established a supportive housing special fund to be administered by the corporation for the purpose of developing, operating, and maintaining affordable, permanent housing and the provision of supportive services for individuals or families with special needs.
(b) Moneys in the fund may be used to:
(1) Make loans to finance the development, pre-development, construction, acquisition, preservation, or substantial rehabilitation of supportive housing projects;
(2) Make project-based rental assistance payments;
(3) Make payments for supportive services for households residing in the supportive housing projects; and
(4) For other housing services or activities as provided in rules adopted by the corporation without regard to chapter 91.
(c) The fund may include sums appropriated by the legislature, private contributions, proceeds from repayment of loans, interest, fees, other returns, and moneys from other sources.
(d) An amount from the fund, to be set by the corporation and authorized by the legislature, may be used for administrative expenses incurred by the corporation in administering the fund; provided that moneys in the fund shall not be used to finance day-to-day administrative expenses of the projects allotted moneys from the fund.
(e) The corporation shall consult with the counties and community-based organizations to leverage funds and obtain input on selection of projects.
(f) The corporation may contract with other executive branch departments or agencies, the counties, or private or nonprofit organizations as necessary for the provision of supportive housing and services. The corporation shall be exempt from chapter 103D in selecting a qualified private or nonprofit organization to assist with the development and maintenance of supportive housing and provision of rental assistance and supportive services. The corporation may, without regard to chapter 91, establish rules and qualification standards for participants of the supportive housing program.
(g) The corporation may establish, revise, charge, and collect a reasonable service fee, as necessary, in connection with its financing, services, and approvals under this subpart. The fees shall be deposited into the supportive housing special fund.
(h) The corporation shall submit a report to the legislature no later than twenty days prior to the convening of each regular session describing the projects funded using moneys from the supportive housing special fund.
§201H-B Additional powers. The powers conferred upon the corporation by this subpart shall be in addition and supplemental to the powers conferred by any other law, and nothing in this subpart shall be construed as limiting any powers, rights, privileges, or immunities conferred."
SECTION 3. Section 247-2, Hawaii Revised Statutes, is amended to read as follows:
"§247-2 Basis and rate of tax. (a) The tax imposed by section 247-1 shall be based on the actual and full consideration (whether cash or otherwise, including any promise, act, forbearance, property interest, value, gain, advantage, benefit, or profit), paid or to be paid for all transfers or conveyance of realty or any interest therein, that shall include any liens or encumbrances thereon at the time of sale, lease, sublease, assignment, transfer, or conveyance, and shall be at the following rates:
(1) Except as provided in paragraph (2):
(A) [Ten cents per
$100 for] For properties with a value of less than $600,000[;]: 10 cents per $100;
(B) [Twenty cents
per $100 for] For properties with a value of at least $600,000, but
less than $1,000,000[;]: $600
plus 35 cents per $100 of excess over $600,000;
(C) [Thirty
cents per $100 for] For properties with a value of at least
$1,000,000, but less than $2,000,000[;]: $2,000 plus 60 cents per $100 of excess over
$1,000,000;
(D) [Fifty
cents per $100 for] For properties with a value of at least
$2,000,000, but less than $4,000,000[;]: $8,000 plus 85 cents per $100 of excess over
$2,000,000;
(E) [Seventy
cents per $100 for] For properties with a value of at least
$4,000,000, but less than $6,000,000[;]: $25,000 plus $1.20 per $100 of excess over $4,000,000;
(F) [Ninety
cents per $100 for] For properties with a value of at least
$6,000,000, but less than $10,000,000[; and]: $49,000 plus $1.75 per $100 of excess over
$6,000,000; and
(G) [One
dollar per $100 for] For properties with a value of at least
$10,000,000 [or greater; and]: $119,000 plus $3 per $100 of excess
over $10,000,000; and
(2) For the sale of a condominium or single family residence for which the purchaser is ineligible for a county homeowner's exemption on property tax:
(A) [Fifteen cents
per $100 for] For properties with a value of less than $600,000[;]: 15 cents per $100;
(B) [Twenty-five
cents per $100 for] For properties with a value of at least
$600,000, but less than $1,000,000[;]: $900 plus 40 cents per $100 of excess over
$600,000;
(C) [Forty
cents per $100 for] For properties with a value of at least
$1,000,000, but less than $2,000,000[;]: $2,500 plus 65 cents per $100 of excess over
$1,000,000;
(D) [Sixty
cents per $100 for] For properties with a value of at least
$2,000,000, but less than $4,000,000[;]: $9,000 plus $2.00 per $100 of excess over
$2,000,000;
(E) [Eighty-five
cents per $100 for] For properties with a value of at least
$4,000,000, but less than $6,000,000[;]: $49,000 plus $2.50 per $100 of excess over
$4,000,000; and
(F) [One
dollar and ten cents per $100 for] For properties with a value of at
least $6,000,000, but less than $10,000,000[; and]: $99,000 plus $3.25 per $100 of excess over
$6,000,000; and
(G) [One
dollar and twenty-five cents per $100 for] For properties with a
value of $10,000,000 or greater[,]: $229,000 plus $4.10 per $100 of excess over
$10,000,000,
of [such] the actual and full
consideration; provided that in the case of a lease or sublease, this chapter
shall apply only to a lease or sublease whose full unexpired term is for a
period of five years or more[, and in those cases, including (where
appropriate) those cases where the]; provided further that if a
lease has been extended or amended, the tax in this chapter shall be based on
the cash value of the lease rentals discounted to present day value and
capitalized at the rate of six per cent, plus the actual and full consideration
paid or to be paid for any and all improvements, if any, that shall include
on-site as well as off-site improvements, applicable to the leased premises;
and provided further that the tax imposed for each transaction shall be [not]
no less than $1.
The rates in this section shall apply to the transfer or conveyance of a multifamily residential property; provided that "value", for purposes of determining the applicable rate, shall be an amount calculated by dividing the actual and full consideration by the number of residential dwelling units in the property; provided further that the tax shall be calculated by applying the applicable rate to the actual and full consideration for the transfer or conveyance of realty or any interest therein. As used in this subsection, "multifamily residential property" means a structure that is located within the state urban land use district and divided into five or more dwelling units.
(b) For each taxable year beginning after December 31, 2025, the director of taxation, no later than December 15 of the preceding calendar year, shall recompute the rates in subsection (a) by multiplying the dollar amount for the preceding taxable year by the cost-of-living adjustment factor, if the cost-of-living adjustment factor is greater than zero, and rounding off the resulting product to the nearest $1. If the cost-of-living adjustment factor is less than or equal to zero in a given year, then no adjustment shall occur in the following year.
As used in this subsection, "cost-of-living adjustment factor" means a factor calculated by adding 1.0 to the percentage change in the Consumer Price Index for All Urban Consumers, as published by the United States Department of Labor, from July of the preceding calendar year to July of the current calendar year; provided that if the Consumer Price Index is discontinued, the Chained Consumer Price Index for All Urban Consumers, as published by the United States Department of Labor, shall be used to calculate the cost-of-living adjustment factor."
SECTION 4. Section 247-7, Hawaii Revised Statutes, is amended to read as follows:
"§247-7 Disposition of taxes. All taxes collected under this chapter shall be paid into the state treasury to the credit of the general fund of the State, to be used and expended for the purposes for which the general fund was created and exists by law; provided that of the taxes collected each fiscal year:
(1) [Ten]
Eight per cent or [$5,100,000,] $10,000,000, whichever
is less, shall be paid into the land conservation fund established pursuant to
section 173A-5; [and]
(2) [Fifty]
Thirty-eight per cent or [$38,000,000,] $50,000,000,
whichever is less, shall be paid into the rental housing revolving fund
established by section 201H-202[.];
(3) Eight per cent or $10,000,000, whichever is less, shall be paid into the supportive housing special fund established pursuant to section 201H-A; and
(4) Ten per cent shall be paid into the dwelling unit revolving fund established pursuant to section 201H-191 to fund infrastructure programs in county-designated transit-oriented development zones or districts that meet minimum standards of transit-supportive density; provided that these standards shall be met in order for any state or county agency or any private entity to receive funding from the dwelling unit revolving fund pursuant to this paragraph.
As used in this section, "transit-supportive density" means a floor area ratio of at least:
(1) 4.0 for all uses that are permitted in a county-designated transit-oriented development area or by the underlying county zoning;
(2) 6.0 for all uses that are permitted in a county-designated transit-oriented development area within one-half mile of a station of a locally preferred alternative for a mass transit project; and
(3) For all uses that are permitted within one-quarter mile of a station of a locally preferred alternative for a mass transit project, whichever is greater:
(A) 7.0;
(B) The maximum floor area ratio allowed by the adopted transit-oriented development special district; or
(C) The maximum floor area ratio allowed by the applicable transit-oriented development plan."
SECTION 5. This Act does not affect rights and duties that matured, penalties that were incurred, and proceedings that were begun before its effective date.
SECTION 6. In codifying the new sections added by section 2 of this Act, the revisor of statutes shall substitute appropriate section numbers for the letters used in designating the new sections in this Act.
SECTION 7. Statutory material to be repealed is bracketed and stricken. New statutory material is underscored.
SECTION 8. This Act shall take effect on July 1, 2025.
|
INTRODUCED BY: |
_____________________________ |
|
|
|
Report Title:
Conveyance Tax; Supportive Housing Special Fund; Dwelling Unit Revolving Fund; Infrastructure Funding; County-designated Transit-oriented Development
Description:
Establishes the Supportive Housing Special Fund. Restructures the conveyance tax to a marginal rate system and adjusts the tax for multifamily properties to reflect value on a per-unit basis. Allocates revenues from conveyance tax collections to the Supportive Housing Special Fund. Allocates a portion of conveyance tax collections to the Dwelling Unit Revolving Fund to fund infrastructure programs in county-designated transit-oriented development areas that meet minimum standards of transit-supportive density.
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
Date
|
Status
|
|---|---|
| Feb 2, 2026 | Re-Referred to HOU/WLA, WAM. |
| Dec 8, 2025 | Carried over to 2026 Regular Session. |
| Mar 6, 2025 | Referred to HOU/WTL, WAM. |
| Mar 6, 2025 | Passed First Reading. |
| Mar 6, 2025 | Received from House (Hse. Com. No. 368). |
| Mar 4, 2025 | Passed Third Reading with Representative(s) Reyes Oda voting aye with reservations; Representative(s) Alcos, Garcia, Kong, Matsumoto, Muraoka, Shimizu voting no (6) and Representative(s) Pierick, Ward excused (2). Transmitted to Senate. |
| Feb 28, 2025 | Reported from FIN (Stand. Com. Rep. No. 1124), recommending passage on Third Reading. |
| Feb 25, 2025 | The committee on FIN recommend that the measure be PASSED, UNAMENDED. The votes were as follows: 13 Ayes: Representative(s) Yamashita, Takenouchi, Grandinetti, Holt, Hussey, Keohokapu-Lee Loy, Kusch, Lamosao, Lee, M., Miyake, Morikawa, Templo; Ayes with reservations: Representative(s) Reyes Oda; 1 Noes: Representative(s) Alcos; and 2 Excused: Representative(s) Kitagawa, Ward. |
| Feb 21, 2025 | Bill scheduled to be heard by FIN on Tuesday, 02-25-25 10:00AM in House conference room 308 VIA VIDEOCONFERENCE. |
| Feb 14, 2025 | Report adopted; referred to the committee(s) on FIN as amended in HD 2 with Representative(s) Alcos, Matsumoto, Reyes Oda voting aye with reservations; Representative(s) Garcia, Muraoka, Pierick voting no (3) and Representative(s) Cochran, Matayoshi, Poepoe, Ward excused (4). |
| Feb 14, 2025 | Reported from WAL (Stand. Com. Rep. No. 711) as amended in HD 2, recommending referral to FIN. |
| Feb 13, 2025 | The committee on WAL recommend that the measure be PASSED, WITH AMENDMENTS. The votes were as follows: 8 Ayes: Representative(s) Hashem, Lamosao, Belatti, Ichiyama, Morikawa, Shimizu, Souza; Ayes with reservations: Representative(s) Iwamoto; Noes: none; and 2 Excused: Representative(s) Poepoe, Woodson. |
| Feb 10, 2025 | Bill scheduled to be heard by WAL on Thursday, 02-13-25 9:30AM in House conference room 411 VIA VIDEOCONFERENCE. |
| Feb 6, 2025 | Passed Second Reading as amended in HD 1 and referred to the committee(s) on WAL with Representative(s) Alcos, Matsumoto voting aye with reservations; Representative(s) Garcia, Muraoka, Pierick voting no (3) and Representative(s) Ward excused (1). |
| Feb 6, 2025 | Reported from HSG (Stand. Com. Rep. No. 221) as amended in HD 1, recommending passage on Second Reading and referral to WAL. |
| Jan 29, 2025 | The committee on HSG recommend that the measure be PASSED, WITH AMENDMENTS. The votes were as follows: 6 Ayes: Representative(s) Evslin, Miyake, Grandinetti, Kila, Kitagawa, La Chica; Ayes with reservations: none; 2 Noes: Representative(s) Muraoka, Pierick; and 1 Excused: Representative(s) Cochran. |
| Jan 27, 2025 | Bill scheduled to be heard by HSG on Wednesday, 01-29-25 9:15AM in House conference room 430 VIA VIDEOCONFERENCE. |
| Jan 27, 2025 | Referred to HSG, WAL, FIN, referral sheet 4 |
| Jan 23, 2025 | Introduced and Pass First Reading. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Mar 4, 2025 | Third Reading | House Floor |
Passed |
|
| Feb 25, 2025 | The committee on FIN recommend that the measure be PASSED, UNAMENDED | House Standing Committee on Finance |
Passed |
|
| Feb 13, 2025 | The committee on WAL recommend that the measure be PASSED, WITH AMENDMENTS | House Standing Committee on Water & Land |
Passed |
|
| Jan 29, 2025 | The committee on HSG recommend that the measure be PASSED, WITH AMENDMENTS | House Standing Committee on Housing |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| Catholic Charities Hawaii | ** Support | |
| Church of the Crossroads | ** Support | |
| Grassroot Institute of Hawaii | *** Against | Feb 25, 2025 |
| Hawaii Appleseed Center for Law & Economic Justice | ** Support | |
| Hawaii Housing Finance and Development Corporation | *** Support | Feb 25, 2025 |
| Hawaii Children's Action Network Speaks! | ** Support | |
| Hawaii Health & Harm Reduction Center | ** Support | |
| Hawaiʻi Association of REALTORS | ** Against | |
| Hawai‘i County Council - District 2 | *** Support | Feb 12, 2025 |
| Hawai‘i State Council on Developmental Disabilities | *** Support | Feb 25, 2025 |
| League of Women Voters of Hawaii | ** Support | |
| Office of Planning and Sustainable Development | ** Support | |
| Save Medicaid Hawaii | ** Support | |
| State Council on Developmental Disabilities | ** Support | |
| State of Hawai‘i Legacy Land Conservation Commission | *** Support | Feb 12, 2025 |
| the Land Use Research Foundation of Hawaii | ** Against | |
| The Nature Conservancy Hawaii and Palmyra | ** Support |
STAND. COM. REP. NO. 1124
Honolulu, Hawaii
, 2025
RE: H.B. No. 1410
H.D. 2
Honorable Nadine K. Nakamura
Speaker, House of Representatives
Thirty-Third State Legislature
Regular Session of 2025
State of Hawaii
Madame:
Your Committee on Finance, to which was referred H.B. No. 1410, H.D. 2, entitled:
"A BILL FOR AN ACT RELATING TO HOUSING,"
begs leave to report as follows:
The purpose of this measure is to:
(1) Establish the Supportive Housing Special Fund;
(2) Restructure the conveyance tax to a marginal rate system and adjust the tax for multifamily residential properties to reflect value on a per-unit basis;
(3) Allocate a portion of conveyance tax revenues to the Supportive Housing Special Fund; and
(4) Allocate a portion of conveyance tax revenues to the Dwelling Unit Revolving Fund to fund infrastructure programs in county-designated transit-oriented development areas that meet minimum standards of transit-supportive density.
Your Committee received testimony in support of this measure from the State Council on Developmental Disabilities; Church of the Crossroads; Hawaii Children's Action Network Speaks!; Hawaii Health & Harm Reduction Center; Hawaii Appleseed Center for Law & Economic Justice; League of Women Voters of Hawaii; Catholic Charities Hawaii; Save Medicaid Hawaii; and eight individuals. Your Committee received testimony in opposition to this measure from the Land Use Research Foundation of Hawaii; Hawaiʻi Association of REALTORS; and one individual. Your Committee received comments on this measure from the Department of Land and Natural Resources; Department of Budget and Finance; Department of Taxation; Hawaii Housing Finance and Development Corporation; Office of Planning and Sustainable Development; The Nature Conservancy, Hawaii and Palmyra; Grassroot Institute of Hawaii; Tax Foundation of Hawaii; and one individual.
As affirmed by the record of votes of the members of your Committee on Finance that is attached to this report, your Committee is in accord with the intent and purpose of H.B. No. 1410, H.D. 2, and recommends that it pass Third Reading.
Respectfully submitted on behalf of the members of the Committee on Finance,
|
|
|
____________________________ KYLE T. YAMASHITA, Chair |
|
|
|
|
STAND. COM. REP. NO. 711
Honolulu, Hawaii
, 2025
RE: H.B. No. 1410
H.D. 2
Honorable Nadine K. Nakamura
Speaker, House of Representatives
Thirty-Third State Legislature
Regular Session of 2025
State of Hawaii
Madame:
Your Committee on Water & Land, to which was referred H.B. No. 1410, H.D. 1, entitled:
"A BILL FOR AN ACT RELATING TO HOUSING,"
begs leave to report as follows:
The purpose of this measure is to:
(1) Establish the Supportive Housing Special Fund;
(2) Restructure the conveyance tax to a marginal rate system and adjust the tax for multifamily properties to reflect value on a per-unit basis;
(3) Allocate a portion of conveyance tax revenues to the Supportive Housing Special Fund; and
(4) Allocate a portion of conveyance tax revenues to the Dwelling Unit Revolving Fund to fund infrastructure programs in county-designated transit-oriented development areas that meet minimum standards of transit-supportive density.
Your Committee received testimony in support of this measure from the Hawaii Housing Finance and Development Corporation; Hawaii State Council on Developmental Disabilities; Office of Planning and Sustainable Development; one member of the Hawaii County Council; Hawaii Appleseed Center for Law & Economic Justice; Catholic Charities Hawaii; Hawaii Children's Action Network Speaks!; The Nature Conservancy Hawaii and Palmyra; and two individuals. Your Committee received testimony in opposition to this measure from the Hawaii Association of REALTORS and Land Use Research Foundation of Hawaii. Your Committee received comments on this measure from the Department of Land and Natural Resources; Department of Taxation; Tax Foundation of Hawaii; Grassroot Institute of Hawaii; and one individual.
Your Committee finds that the State's affordable housing crisis is exacerbated by inadequate infrastructure funding and a lack of stable financing, particularly for supportive housing. Your Committee further finds that encouraging transit-oriented development will help the State achieve its climate and energy goals by promoting the creation of sustainable, walkable communities that reduce reliance on cars, lower carbon emissions, and support local businesses. By restructuring the conveyance tax to a marginal rate system and increasing rates on high-value non-owner-occupied homes, as proposed by this measure, the State will be able to generate dedicated revenue for affordable and supportive housing projects that are vital to the community.
Your Committee has amended this measure by:
(1) Making agriculturally zoned lands with a residential dwelling unit for which the purchaser is ineligible for a county homeowner's real property tax exemption subject to the non-owner occupied conveyance tax rates; and
(2) Making technical, nonsubstantive amendments for the purposes of clarity, consistency, and style.
As affirmed by the record of votes of the members of your Committee on Water & Land that is attached to this report, your Committee is in accord with the intent and purpose of H.B. No. 1410, H.D. 1, as amended herein, and recommends that it be referred to your Committee on Finance in the form attached hereto as H.B. No. 1410, H.D. 2.
Respectfully submitted on behalf of the members of the Committee on Water & Land,
|
|
|
____________________________ MARK J. HASHEM, Chair |
|
|
|
|
STAND. COM. REP. NO. 221
Honolulu, Hawaii
, 2025
RE: H.B. No. 1410
H.D. 1
Honorable Nadine K. Nakamura
Speaker, House of Representatives
Thirty-Third State Legislature
Regular Session of 2025
State of Hawaii
Madame:
Your Committee on Housing, to which was referred H.B. No. 1410 entitled:
"A BILL FOR AN ACT RELATING TO HOUSING,"
begs leave to report as follows:
The purpose of this measure is to:
(1) Establish the Supportive Housing Special Fund;
(2) Restructure the conveyance tax to a marginal rate system and adjust the tax for multifamily properties to reflect value on a per-unit basis;
(3) Allocate revenues from conveyance tax collections to the Supportive Housing Special Fund; and
(4) Allocate a portion of conveyance tax collections to the Dwelling Unit Revolving Fund to fund infrastructure programs in county-designated transit-oriented development zones or districts that meet minimum standards of transit-supportive density.
Your Committee received testimony in support of this measure from the Hawaii Housing Finance and Development Corporation; Catholic Charities Hawaiʻi; Hawaii Appleseed Center for Law & Economic Justice; and one individual. Your Committee received testimony in opposition to this measure from the Hawaii Association of REALTORS; and Land Use Research Foundation of Hawaii. Your Committee received comments on this measure from the Department of Land and Natural Resources; Department of Taxation; Department of Budget and Finance; Tax Foundation of Hawaii; and Grassroot Institute of Hawaii.
Your Committee finds that the State's affordable housing crisis requires immediate action to ensure sustainable growth. The existing funding mechanisms for affordable housing and supportive services are fragmented and insufficient, leaving many vulnerable populations without stable housing. This measure will restructure the conveyance tax, thereby generating dedicated revenue for affordable and supportive housing projects.
Your Committee notes the concern raised in testimony that this measure could potentially discourage adaptive reuse and your Committee will continue to work to address this concern as this measure moves through the legislative process.
Your Committee has amended this measure by:
(1) Requiring proceeds from the conveyance tax deposited into the Dwelling Unit Revolving Fund to only be used to fund infrastructure programs in areas that meet minimum standards of transit-supportive density requirements;
(2) Inserting definitions for "county-designated transit-oriented development area", "floor area ratio", and "ministerial";
(3) Amending the definition of "transit-supportive density" to include certain development standards and other requirements;
(4) Clarifying the calculation of the cost-of-living adjustments to conveyance tax rates;
(5) Changing the effective date to July 1, 3000, to encourage further discussion; and
(6) Making technical, nonsubstantive amendments for the purposes of clarity, consistency, and style.
Your Committee notes that the Department of Taxation has requested an effective date of January 1, 2026, for this measure, to give the Department sufficient time to make changes necessary for the conveyance tax rate changes and amendments to the allocation of revenues.
As affirmed by the record of votes of the members of your Committee on Housing that is attached to this report, your Committee is in accord with the intent and purpose of H.B. No. 1410, as amended herein, and recommends that it pass Second Reading in the form attached hereto as H.B. No. 1410, H.D. 1, and be referred to your Committee on Water & Land.
Respectfully submitted on behalf of the members of the Committee on Housing,
|
|
|
____________________________ LUKE A. EVSLIN, Chair |
|
|
|
|
|
Date
|
Testimony PDF
|
|---|---|
| Feb 25, 2025 | HB1410_HD2_TESTIMONY_FIN_02-25-25_.PDF |
| Feb 12, 2025 | HB1410_HD1_TESTIMONY_WAL_02-13-25_.PDF |
| Jan 29, 2025 | HB1410_TESTIMONY_HSG_01-29-25_.PDF |
Discussed in Hearing
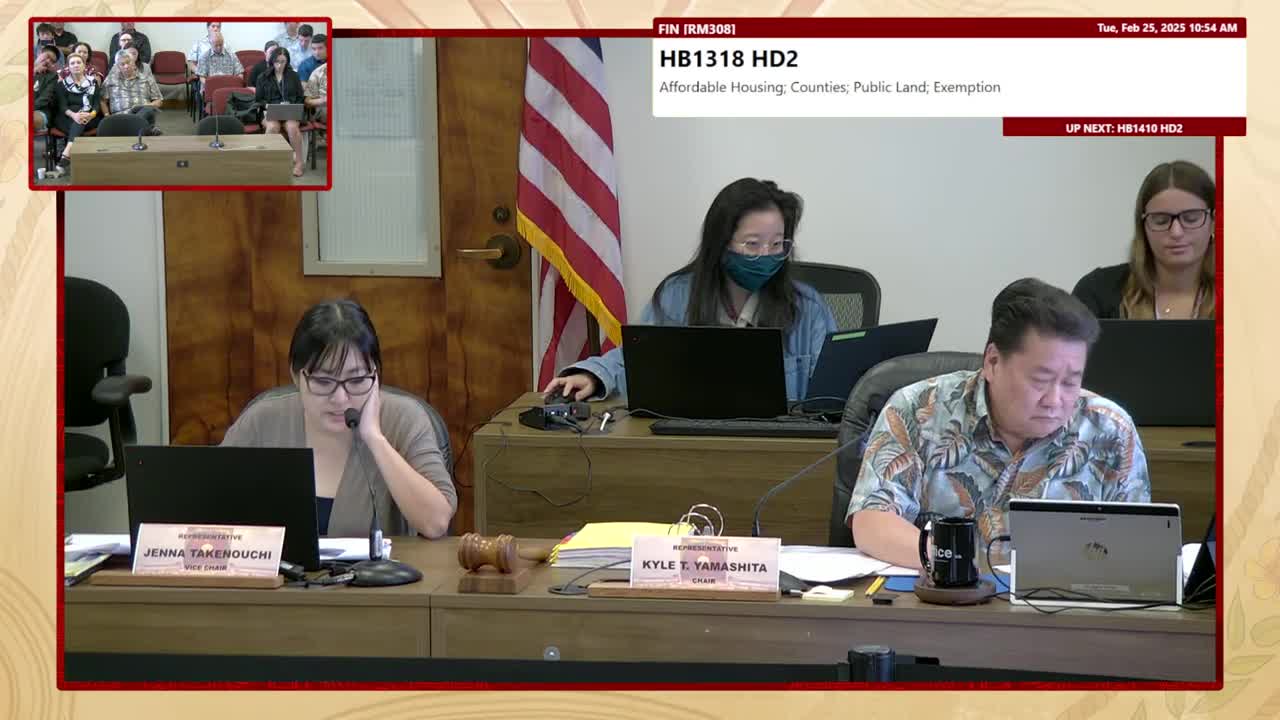 14MIN
House Standing Committee on Finance
 6MIN
House Standing Committee on Water & Land
 9MIN
House Standing Committee on Housing
Bill Author