SB 2935: GET; Exemptions; Feminine Hygiene Products
- Session Year: 2025-2026
- House: Senate
- Latest Version Date: 2026-02-19
Current Status:
Failed
(2026-02-20: Report adopted; Passed Second Reading, as amended (SD 1) and referred to WAM.)
Introduced
In Committee
First Chamber
In Committee
Second Chamber
Final Decking
Enacted
What does this bill do?
The bill would make feminine hygiene products exempt from Hawaii's general excise tax. It covers sales of items such as sanitary napkins and towels, tampons, panty liners, menstrual cups, douches, and vaginal hygiene creams, foams, ointments, jellies, powders, and sprays.
The summary is provided by generative AI which can make mistakes. For original language, please view the details in the table below.
Establishes a general excise tax exemption for the gross proceeds or income from feminine hygiene products. Effective 1/30/2050. (SD1)
Establishes a general excise tax exemption for the gross proceeds or income from the sale of groceries that are eligible under the Supplemental Nutrition Assistance Program and Special Supplemental Nutrition Program for Women, Infants, and Children, regardless of the means of purchase and the program eligibility of the purchaser; nonprescription drugs and medical supplies; feminine hygiene products; and diapers. Effective 1/1/2027.
|
THE SENATE |
S.B. NO. |
2935 |
|
THIRTY-THIRD LEGISLATURE, 2026 |
S.D. 1 |
|
|
STATE OF HAWAII |
|
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
RELATING TO GENERAL EXCISE TAX EXEMPTIONS.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
SECTION 1. Chapter 237, Hawaii Revised Statutes, is amended by adding a new section to be appropriately designated and to read as follows:
"§237- Exemption for feminine hygiene products. There shall be exempted from, and excluded from the measure of, the taxes imposed by this chapter all of the gross proceeds or income received from the sale of feminine hygiene products, including but not limited to sanitary napkins; sanitary towels; tampons; panty liners; douches; feminine hygiene syringes; menstrual cups; and creams, foams, ointments, jellies, powders, and sprays used for vaginal hygiene purposes."
SECTION 2. New statutory material is underscored.
SECTION 3. This Act shall take effect on January 30, 2050.
Report Title:
GET; Exemptions; Feminine Hygiene Products
Description:
Establishes a general excise tax exemption for the gross proceeds or income from feminine hygiene products. Effective 1/30/2050. (SD1)
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
THE SENATE |
S.B. NO. |
2935 |
|
THIRTY-THIRD LEGISLATURE, 2026 |
|
|
|
STATE OF HAWAII |
|
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
relating to general excise tax exemptions.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
SECTION 1. Chapter 237, Hawaii Revised Statutes, is amended by adding four new sections to be appropriately designated and to read as follows:
"§237- Exemption for eligible groceries. (a) There shall be exempted from, and excluded from the measure of, the taxes imposed by this chapter all of the gross proceeds or income received from the sale of all groceries eligible for purchase under the Supplemental Nutrition Assistance Program and Special Supplemental Nutrition Program for Women, Infants, and Children within the State, regardless of the means of purchase and the eligibility of the purchaser for Supplemental Nutrition Assistance Program or Special Supplemental Nutrition Program for Women, Infants, and Children benefits.
(b) For the purposes of this section:
"Food" or "food product" means substances, whether in liquid, concentrated, solid, frozen, dried, or dehydrated form, that are sold for ingestion or chewing by humans and are consumed for their taste or nutritional value.
"Groceries" means any food or food product for home consumption. "Groceries" may be further defined by the department of taxation by rule or tax information release; provided that the department shall consult with the federal Food and Nutrition Service of the United States Department of Agriculture in further defining the term "groceries" for purposes of the Supplemental Nutrition Assistance Program and Special Supplemental Nutrition Program for Women, Infants, and Children.
§237- Exemption for nonprescription drugs and medical supplies. (a) There shall be exempted from, and excluded from the measure of, the taxes imposed by this chapter all of the gross proceeds or income received from the sale of nonprescription drugs and medical supplies.
(b) For the purposes of this section:
"Drug" means:
(1) Articles recognized in the official United States Pharmacopeia, official United States Pharmacopeia Dispensing Information, official Homeopathic Pharmacopoeia of the United States, or official National Formulary, or any supplement to any of these publications;
(2) Articles intended for use in the diagnosis, cure, mitigation, treatment, or prevention of disease in humans or animals;
(3) Articles, other than food or clothing, intended to affect the structure or any function of the body of humans or animals; or
(4) Articles intended for use as a component of any article specified in paragraph (1), (2), or (3); provided that the term "drug" does not include devices or their components, parts or accessories, cosmetics, or liquor as defined in section 281-1.
"Health care facility" has the same meaning as defined in section 323D-2.
"Medical supplies" means items for medical use that are suitable for use in a health care facility or in the home.
"Nonprescription drug" means any packaged, bottled, or nonbulk chemical, drug, or medicine that may be lawfully sold without a practitioner's order.
§237- Exemption for feminine hygiene products. There shall be exempted from, and excluded from the measure of, the taxes imposed by this chapter all of the gross proceeds or income received from the sale of feminine hygiene products, including but not limited to sanitary napkins; sanitary towels; tampons; panty liners; douches; feminine hygiene syringes; menstrual cups; and creams, foams, ointments, jellies, powders, and sprays used for vaginal hygiene purposes.
§237- Exemption for diapers. (a) There shall be exempted from, and excluded from the measure of, the taxes imposed by this chapter all the gross proceeds or income from the sale of diapers.
(b) For the purposes of this section, "diaper" means a washable or disposable absorbent garment that may be worn by an infant or toddler who is not toilet-trained; provided that, if disposable:
(1) Does not contain any latex or common allergens; and
(2) Meets or exceeds the quality standards for diapers commercially available through retail sale in the following categories:
(A) Absorbency (with acceptable rates for first and second wetting);
(B) Waterproof outer cover;
(C) Flexible leg openings; and
(D) Refastening closures."
SECTION 2. New statutory material is underscored.
SECTION 3. This Act shall take effect on January 1, 2027.
|
INTRODUCED BY: |
_____________________________ |
|
|
|
Report Title:
GET; Exemptions; Groceries; Nonprescription Drugs and Medical Supplies; Feminine Hygiene Products; Diapers
Description:
Establishes a general excise tax exemption for the gross proceeds or income from the sale of groceries that are eligible under the Supplemental Nutrition Assistance Program and Special Supplemental Nutrition Program for Women, Infants, and Children, regardless of the means of purchase and the program eligibility of the purchaser; nonprescription drugs and medical supplies; feminine hygiene products; and diapers. Effective 1/1/2027.
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
Date
|
Status
|
|---|---|
| Feb 20, 2026 | Report adopted; Passed Second Reading, as amended (SD 1) and referred to WAM. |
| Feb 20, 2026 | Reported from HHS (Stand. Com. Rep. No. 2573) with recommendation of passage on Second Reading, as amended (SD 1) and referral to WAM. |
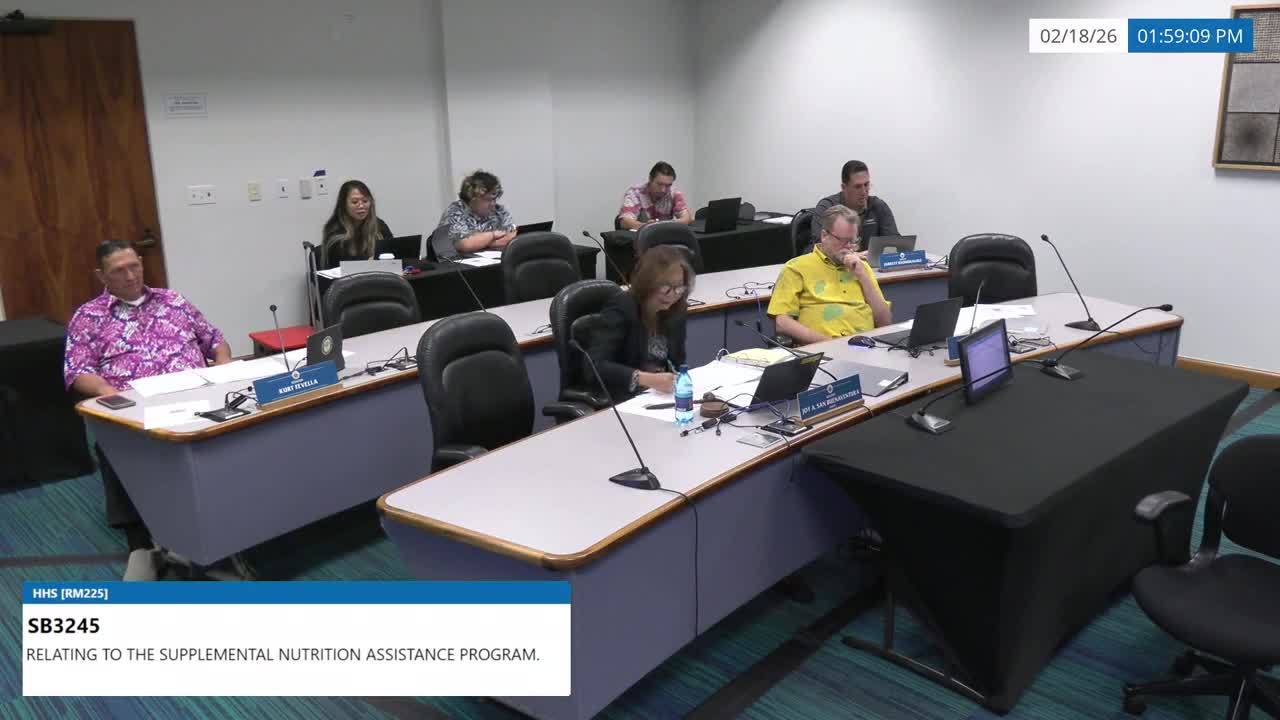
| Feb 18, 2026 | The committee(s) on HHS recommend(s) that the measure be PASSED, WITH AMENDMENTS. The votes in HHS were as follows: 5 Aye(s): Senator(s) San Buenaventura, McKelvey, Kanuha, Keohokalole, Fevella; Aye(s) with reservations: none ; 0 No(es): none; and 0 Excused: none. |
| Feb 13, 2026 | The committee(s) on HHS has scheduled a public hearing on 02-18-26 1:00PM; Conference Room 225 & Videoconference. |
| Jan 30, 2026 | Referred to HHS, WAM. |
| Jan 26, 2026 | Passed First Reading. |
| Jan 23, 2026 | Introduced. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Feb 18, 2026 | The committee(s) on HHS recommend(s) that the measure be PASSED, WITH AMENDMENTS | Senate Standing Committee on Health and Human Services |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| AlohaCare | *** Support | Feb 18, 2026 |
| AlohaCare | ** Support | |
| Consumer Healthcare Products Association, Holomua Collaborative | ** Support | |
| Consumer Healthcare Products Association | *** Support | Feb 18, 2026 |
| Grassroot Institute of Hawaii | ** Support | |
| Hawaii Appleseed Center for Law & Economic Justice | ** Support | |
| Hawaii Food Industry Association | ** Support | |
| Hawaii Public Health Institute | ** Support | |
| Holomua Collaborative | *** Support | Feb 18, 2026 |
| Kingdom of The Hawaiian Islands | *** Support | Feb 18, 2026 |
| Ohana Unity Party | *** Support | Feb 18, 2026 |
STAND. COM. REP. NO. 2573
Honolulu, Hawaii
RE: S.B. No. 2935
S.D. 1
Honorable Ronald D. Kouchi
President of the Senate
Thirty-Third State Legislature
Regular Session of 2026
State of Hawaii
Sir:
Your Committee on Health and Human Services, to which was referred S.B. No. 2935 entitled:
"A BILL FOR AN ACT RELATING TO GENERAL EXCISE TAX EXEMPTIONS,"
begs leave to report as follows:
The purpose and intent of this measure is to establish a general excise tax exemption for the gross proceeds or income from the sale of:
(1) Groceries that are eligible under the Supplemental Nutrition Assistance Program and Special Supplemental Nutrition Program for Women, Infants, and Children, regardless of the means of purchase and the program eligibility of the purchaser;
(2) Nonprescription drugs and medical supplies;
(3) Feminine hygiene products; and
(4) Diapers.
Your Committee received testimony in support of this measure from the Hawaii Public Health Institute; Grassroot Institute of Hawaii; Hawaii Food Industry Association; AlohaCare; Hawaii Appleseed Center for Law & Economic Justice; Consumer Healthcare Products Association, Holomua Collaborative; and three individuals.
Your Committee received testimony in opposition to this measure from one individual.
Your Committee received comments on this measure from the Department of Taxation and Tax Foundation of Hawaii.
Your Committee finds that the cost of living in the State is among the highest in the nation, with many residents struggling to afford basic necessities. Your Committee further finds that many essentials are taxed under the general excise tax at each stage of the supply chain, which contributes to higher overall costs and makes this regressive tax harder on households with the least disposable income. This measure removes the general excise tax from essential items to help deliver financial relief for working class families in the State, improve the regressivity of the State's tax structure, and provide an opportunity for a more just economic system.
Your Committee has amended this measure by:
(1) Deleting language that would have exempted eligible groceries, nonprescription drugs and medical supplies, and diapers from the general excise tax; and
(2) Inserting an effective date of January 30, 2050, to encourage further discussion.
As affirmed by the record of votes of the members of your Committee on Health and Human Services that is attached to this report, your Committee is in accord with the intent and purpose of S.B. No. 2935, as amended herein, and recommends that it pass Second Reading in the form attached hereto as S.B. No. 2935, S.D. 1, and be referred to your Committee on Ways and Means.
Respectfully submitted on behalf of the members of the Committee on Health and Human Services,
|
|
|
________________________________ JOY A. SAN BUENAVENTURA, Chair |
|
|
|
|
|
Date
|
Testimony PDF
|
|---|---|
| Feb 18, 2026 | SB2935_TESTIMONY_HHS_02-18-26_.PDF |
Discussed in Hearing
 2MIN
Senate Standing Committee on Health and Human Services
2MIN
Senate Standing Committee on Health and Human Services
Bill Author