SB 313: RELATING TO A WEALTH ASSET TAX.
- Session Year: 2025-2026
- House: Senate
- Latest Version Date: 2025-02-11
Current Status:
Failed
(2025-12-08: Carried over to 2026 Regular Session.)
Introduced
In Committee
First Chamber
In Committee
Second Chamber
Final Decking
Enacted
Beginning January 1, 2030, establishes a wealth asset tax of one per cent of the state net worth of each individual taxpayer who holds $20,000,000 or more in assets in the State. Effective 4/23/2057. (SD1)
Establishes a wealth asset tax of one per cent of the state net worth of each individual taxpayer who holds $20,000,000 or more in assets in the State.
|
THE SENATE |
S.B. NO. |
313 |
|
THIRTY-THIRD LEGISLATURE, 2025 |
S.D. 1 |
|
|
STATE OF HAWAII |
|
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
RELATING TO A WEALTH ASSET TAX.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
"Chapter
wealth asset tax
§ -1 Definitions. As used in this chapter:
"Department" means the department of taxation.
"Director" means the director of taxation.
"Taxpayer" means a person subject to a tax imposed by this chapter, including individuals, estates, and trusts.
§ -2 Imposition of tax. There is hereby imposed and shall be levied, collected, and paid, a tax on the activity of sustaining excessive accumulations of wealth by every qualified taxpayer.
§ -3 Basis and rate; wealth asset tax. (a) The tax imposed by section -2 shall be one per cent of the state net worth in excess of $20,000,000 for each individual taxpayer who holds more than $20,000,000 in assets in the State; provided that the individual taxpayer's net worth shall be based on the individual's assets, not joint assets, and a married individual shall file a separate return; provided further that if the taxpayer pays a wealth asset tax on the same asset in a different state, the amount paid to the other state shall be subtracted from the state tax liability.
(b) A taxpayer's state net worth shall be determined pursuant to rules adopted by the department; provided that a taxpayer's state net worth shall include but not be limited to the aggregate value of assets in the following categories:
(1) Real Property;
(2) Stock in any publicly and privately traded C‑corporation;
(3) Stock in any S‑corporation;
(4) Interests in any partnership;
(5) Interests in any private equity or hedge fund;
(6) Interests in any other noncorporate business;
(7) Bonds and interest-bearing savings accounts;
(8) Cash and deposits;
(9) Farm assets;
(10) Interest in mutual funds or index funds;
(11) Put and call options on securities;
(12) Futures contracts;
(13) Art and collectables;
(14) Financial assets held offshore;
(15) Pension funds;
(16) Debts owed to the taxpayer; and
(17) Other assets.
§ -4 Reporting and payment. (a) Assets used to determine state net worth pursuant to section -3(b) shall be reported in a form and manner specified by the director.
(b) The tax imposed by this chapter shall be reported with, and payable at the same time as, taxes imposed pursuant to chapter 235; provided that the tax imposed by this chapter shall be due once every three years.
§ -5 Assets belonging to dependents. For the purpose of determining state net worth and tax liability under this chapter, any assets belonging to a person who can be claimed as a dependent that are in excess of $50,000 shall be deemed to be assets of the taxpayer who can claim the person as a dependent.
§ -6 Valuation of assets. Valuation or appraisal of assets reported pursuant to section -3(b) shall be done in a manner specified by the director in accordance with rules adopted by the department.
§ -7 Forms. The director shall prescribe forms to be used in filing returns and reports required by this chapter.
§ -8 Rules. The department shall adopt rules in accordance with chapter 91 to implement this chapter."
SECTION 2. The department of taxation shall submit proposed legislation suggesting the types of debts to be considered in determining net worth, methods to be used for valuation of assets, time periods for which valuation of assets shall occur, methods for allocation and apportionment, withholding requirements, reporting requirements, limitation periods, and audit and assessment provisions for the wealth asset tax established by this Act to the legislature no later than forty days prior to the convening of the regular session of 2027.
SECTION 3. If any provision of this Act, or the application thereof to any person or circumstance, is held invalid, the invalidity does not affect other provisions or applications of the Act that can be given effect without the invalid provision or application, and to this end the provisions of this Act are severable.
SECTION 4. This Act shall take effect on April 23, 2057, and shall apply to taxable years beginning after December 31, 2029.
Report Title:
Department of Taxation; Wealth Asset Tax; Wealth Tax; State Net Worth
Description:
Beginning January 1, 2030, establishes a wealth asset tax of one per cent of the state net worth of each individual taxpayer who holds $20,000,000 or more in assets in the State. Effective 4/23/2057. (SD1)
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
THE SENATE |
S.B. NO. |
313 |
|
THIRTY-THIRD LEGISLATURE, 2025 |
|
|
|
STATE OF HAWAII |
|
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
RELATING TO A WEALTH ASSET TAX.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
"Chapter
wealth asset tax
§ -1 Definitions. As used in this chapter:
"Department" means the department of taxation.
"Director" means the director of taxation.
"Taxpayer" means a person subject to a tax imposed by this chapter, including individuals, estates, and trusts.
§ -2 Imposition of tax. There is hereby imposed and shall be levied, collected, and paid, a tax on the activity of sustaining excessive accumulations of wealth by every qualified taxpayer.
§ -3 Basis and rate; wealth asset tax. (a) The tax imposed by section -2 shall be one per cent of the state net worth in excess of $20,000,000 for each individual taxpayer who holds more than $20,000,000 in assets in the State; provided that the individual taxpayer's net worth shall be based on the individual's assets, not joint assets, and a married individual shall file a separate return; provided further that if the taxpayer pays a wealth asset tax on the same asset in a different state, the amount paid to the other state shall be subtracted from the state tax liability.
(b) A taxpayer's state net worth shall be determined pursuant to rules adopted by the department; provided that a taxpayer's state net worth shall include but not be limited to the aggregate value of assets in the following categories:
(1) Real Property;
(2) Stock in any publicly and privately traded C‑corporation;
(3) Stock in any S‑corporation;
(4) Interests in any partnership;
(5) Interests in any private equity or hedge fund;
(6) Interests in any other noncorporate business;
(7) Bonds and interest-bearing savings accounts;
(8) Cash and deposits;
(9) Farm assets;
(10) Interest in mutual funds or index funds;
(11) Put and call options on securities;
(12) Futures contracts;
(13) Art and collectables;
(14) Financial assets held offshore;
(15) Pension funds;
(16) Debts owed to the taxpayer; and
(17) Other assets.
§ -4 Reporting and payment. (a) Assets used to determine state net worth pursuant to section -3(b) shall be reported in a form and manner specified by the director.
(b) The tax imposed by this chapter shall be reported with, and payable at the same time as, taxes imposed pursuant to chapter 235.
§ -5 Assets belonging to dependents. For the purpose of determining state net worth and tax liability under this chapter, any assets belonging to a person who can be claimed as a dependent that are in excess of $50,000 shall be deemed to be assets of the taxpayer who can claim the person as a dependent.
§ -6 Valuation of assets. Valuation or appraisal of assets reported pursuant to section -3(b) shall be done in a manner specified by the director in accordance with rules adopted by the department.
§ -7 Forms. The director shall prescribe forms to be used in filing returns and reports required by this chapter.
§ -8 Rules. The department shall adopt rules in accordance with chapter 91 to implement this chapter."
SECTION 2. The department of taxation shall submit proposed legislation suggesting the types of debts to be considered in determining net worth, methods to be used for valuation of assets, time periods for which valuation of assets shall occur, methods for allocation and apportionment, withholding requirements, reporting requirements, limitation periods, and audit and assessment provisions for the wealth asset tax established by this Act to the legislature no later than forty days prior to the convening of the regular session of 2026.
SECTION 3. If any provision of this Act, or the application thereof to any person or circumstance, is held invalid, the invalidity does not affect other provisions or applications of the Act that can be given effect without the invalid provision or application, and to this end the provisions of this Act are severable.
SECTION 4. This Act, upon its approval, shall apply to taxable years beginning after December 31, 2025.
|
INTRODUCED BY: |
_____________________________ |
|
|
|
Report Title:
Department of Taxation; Wealth Asset Tax; Wealth Tax; State Net Worth
Description:
Establishes a wealth asset tax of one per cent of the state net worth of each individual taxpayer who holds $20,000,000 or more in assets in the State.
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
Date
|
Status
|
|---|---|
| Dec 8, 2025 | Carried over to 2026 Regular Session. |
| Feb 12, 2025 | Report adopted; Passed Second Reading, as amended (SD 1) and referred to WAM. |
| Feb 12, 2025 | Reported from JDC (Stand. Com. Rep. No. 359) with recommendation of passage on Second Reading, as amended (SD 1) and referral to WAM. |
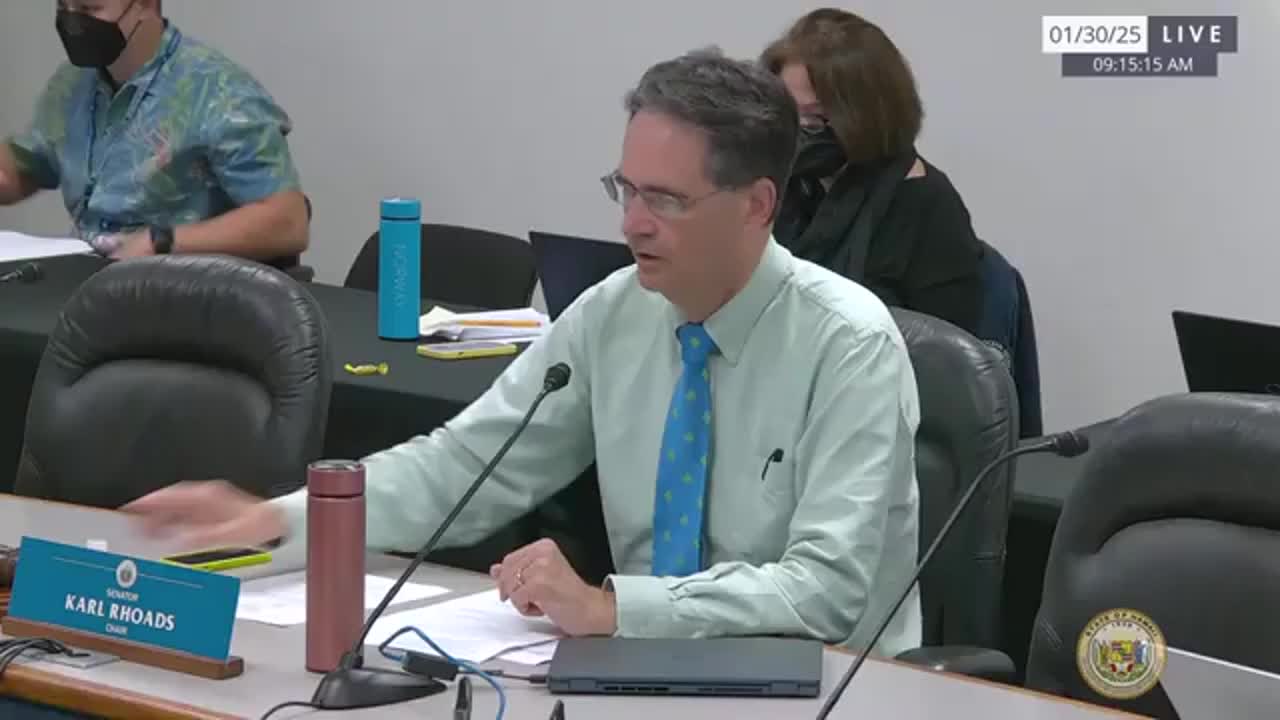
| Jan 30, 2025 | The committee(s) on JDC recommend(s) that the measure be PASSED, WITH AMENDMENTS. The votes in JDC were as follows: 5 Aye(s): Senator(s) Rhoads, Gabbard, Awa; Aye(s) with reservations: Senator(s) Chang, San Buenaventura ; 0 No(es): none; and 0 Excused: none. |
| Jan 27, 2025 | The committee(s) on JDC has scheduled a public hearing on 01-30-25 9:15AM; Conference Room 016 & Videoconference. |
| Jan 21, 2025 | Referred to JDC, WAM. |
| Jan 15, 2025 | Introduced and passed First Reading. |
| Jan 14, 2025 | Pending Introduction. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Jan 30, 2025 | The committee(s) on JDC recommend(s) that the measure be PASSED, WITH AMENDMENTS | Senate Standing Committee on Judiciary |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| Coalition to Save Hawaii's Family Businesses | ** Against | |
| Coalition to Save Hawaii’s Family Businesses | *** Against | Jan 29, 2025 |
| Grassroot Institute of Hawaii | ** Against | |
| Servco Pacific Inc. | *** Against | Jan 29, 2025 |
| Tax Foundation of Hawaii | *** Against | Jan 29, 2025 |
STAND. COM. REP. NO. 359
Honolulu, Hawaii
RE: S.B. No. 313
S.D. 1
Honorable Ronald D. Kouchi
President of the Senate
Thirty-Third State Legislature
Regular Session of 2025
State of Hawaii
Sir:
Your Committee on Judiciary, to which was referred S.B. No. 313 entitled:
"A BILL FOR AN ACT RELATING TO A WEALTH ASSET TAX,"
begs leave to report as follows:
The purpose and intent of this measure is to establish a wealth asset tax of one percent of the state net worth of each individual taxpayer who holds $20,000,000 or more in assets in the State.
Your Committee received testimony in support of this measure from two individuals.
Your Committee received testimony in opposition to this measure from the Coalition to Save Hawaii's Family Businesses, Grassroot Institute of Hawaii, and two individuals.
Your Committee received comments on this measure from the Department of Taxation and Tax Foundation of Hawaii.
Your Committee finds that wealth inequality has a negative economic effect and has been found to lead to higher rates of health and societal problems, including increased obesity, mental illness, homicides, teenage births, incarceration, child conflict, and drug use. Additionally, research has found that societies with higher rates of wealth inequality have decreased rates of life expectancy, educational performance, trust among strangers, and social mobility. Your Committee also finds that extremely wealthy individuals whose state assets exceed $20,000,000 possibly are not contributing their fair share of taxes, thereby further increasing wealth inequality in the State. This category includes numerous wealthy nonresidents who hold assets in the State, which increases real property values and places financial burdens on the residents of the State. Increasing taxes on individuals with many millions of dollars in assets will generate more revenue for the benefit of the State's economy and help to combat wealth inequality. This measure will ensure that individuals with $20,000,000 or more in assets in the State pay their equitable share of taxes.
Your Committee notes the concerns of the Department of Taxation that, since the wealth asset tax established by this measure would be reported and paid on an annual basis with a taxpayer's income tax, the appraisal burden would also be imposed annually, even if the appraisal determines a taxpayer has no liability that year. Your Committee further notes that the Department of Taxation has raised concerns regarding the measure's proposed timeline. Specifically, the Department of Taxation has noted that submitting proposed legislation to the Legislature no later than forty days prior to the Regular Session of 2026 may leave an insufficient amount of time needed to implement steps necessary for the wealth tax that may only be addressed through legislation.
Accordingly, your Committee has amended this measure by:
(1) Requiring the wealth asset tax established by this measure to be due once every three years;
(2) Requiring the Department of Taxation to submit proposed legislation to the Legislature no later than forty days prior to the convening of the Regular Session of 2027, instead of the Regular Session of 2026;
(3) Applying the wealth asset tax to taxable years beginning after December 31, 2029; and
(4) Inserting an effective date of April 23, 2057, to encourage further discussion.
As affirmed by the record of votes of the members of your Committee on Judiciary that is attached to this report, your Committee is in accord with the intent and purpose of S.B. No. 313, as amended herein, and recommends that it pass Second Reading in the form attached hereto as S.B. No. 313, S.D. 1, and be referred to your Committee on Ways and Means.
Respectfully submitted on behalf of the members of the Committee on Judiciary,
|
|
|
________________________________ KARL RHOADS, Chair |
|
|
|
|
|
Date
|
Testimony PDF
|
|---|---|
| Jan 29, 2025 | SB313_TESTIMONY_JDC_01-30-25_.PDF |
Bill Author
Bill Co-Author(s):