SB 138: RELATING TO TAXATION.
- Session Year: 2025-2026
- House: Senate
- Latest Version Date: 2025-02-04
Current Status:
Failed
(2025-12-08: Carried over to 2026 Regular Session.)
Introduced
In Committee
First Chamber
In Committee
Second Chamber
Final Decking
Enacted
Establishes a nonrefundable income tax credit for taxpayers that incur costs related to the design, materials, installation, and construction of hurricane-resistant safe rooms. Effective 7/1/2077. (SD1)
Establishes a nonrefundable income tax credit for taxpayers that incur costs related to the design, materials, installation, and construction of hurricane-resistant safe rooms.
|
THE SENATE |
S.B. NO. |
138 |
|
THIRTY-THIRD LEGISLATURE, 2025 |
S.D. 1 |
|
|
STATE OF HAWAII |
|
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
RELATING TO TAXATION.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
"§235- Safe room installation; income tax credit. (a) There shall be allowed to each taxpayer subject to the tax imposed under this chapter, a nonrefundable safe room installation income tax credit that shall be deductible from the taxpayer's net income tax liability, if any, imposed by this chapter for the taxable year in which the credit is properly claimed.
(b) In the case of a partnership, S corporation, estate, or trust, the tax credit allowable shall be for qualified expenses incurred by the entity for the taxable year. The expenses upon which the tax credit is computed shall be determined at the entity level. Distribution and share of credit shall be determined by rule.
(c) The safe room installation income tax credit shall be equal to per cent of the taxpayer's qualified expenses, up to a maximum of $ .
(d) The total amount of tax credits allowed under this section shall not exceed $ for all taxpayers in any taxable year; provided that any taxpayer who is ineligible to claim the credit in a taxable year due to the $ cap having been exceeded for that taxable year shall be eligible to claim the credit in the subsequent taxable year.
(e) The director of taxation:
(1) Shall prepare any forms that may be necessary to claim a tax credit under this section;
(2) Shall require the taxpayer to furnish reasonable information to verify the claim for the tax credit made under this section, including but not limited to requiring the taxpayer to provide a certification from an architect or structural engineer licensed to practice in the State certifying that the completed safe room or safe rooms satisfy the minimum specifications established by this section; and
(3) May adopt rules under chapter 91 necessary to effectuate the purposes of this section.
(f) The credit allowed under this section shall be claimed against the net income tax liability for the taxable year. If the tax credit under this section exceeds the taxpayer's income tax liability, the excess of the tax credit over liability may be used as a credit against the taxpayer's net income tax liability in subsequent years until exhausted. All claims, including amended claims, for a tax credit under this section shall be filed on or before the end of the twelfth month following the close of the taxable year for which the credit may be claimed. Failure to comply with the foregoing provision shall constitute a waiver of the right to claim the credit.
(g) For the purposes of this section:
"Qualified expenses" means costs that are necessary and directly incurred by the taxpayer for the design, materials, installation, and construction of one or more safe rooms located on the taxpayer's property.
"Safe room" means a windowless room within a residence or within an accessory building to a residence, designed and constructed to resist the effects of wind pressures and to resist impact from windborne debris; provided that the room:
(1) Is not located in a flood zone, storm surge, or other area susceptible to flooding;
(2) Is readily accessible to persons residing within the residence; and
(3) Is designed and constructed pursuant to hurricane standards that are, at a minimum, in compliance with:
(A) Federal Emergency Management Agency Publication 320 "Taking Shelter from the Storm: Building or Installing a Safe Room for Your Home", March 2021 edition, as amended; and
(B) Federal Emergency Management Agency Publication 361 "Safe Rooms for Tornadoes and Hurricanes: Guidance for Community and Residential Safe Rooms", April 2021 edition, as amended.
(h) No other tax credit or deduction shall be claimed under this chapter for qualified expenses for the taxable year."
SECTION 2. New statutory material is underscored.
SECTION 3. This Act shall take effect on July 1, 2077.
Report Title:
Income Tax Credit; Safe Room Installation Income Tax Credit; Hurricane-Resistant Safe Rooms; Director of Taxation
Description:
Establishes a nonrefundable income tax credit for taxpayers that incur costs related to the design, materials, installation, and construction of hurricane-resistant safe rooms. Effective 7/1/2077. (SD1)
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
THE SENATE |
S.B. NO. |
138 |
|
THIRTY-THIRD LEGISLATURE, 2025 |
|
|
|
STATE OF HAWAII |
|
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
relating to taxation.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
"§235- Safe room installation; income tax credit. (a) There shall be allowed to each taxpayer subject to the tax imposed under this chapter, a nonrefundable safe room installation income tax credit that shall be deductible from the taxpayer's net income tax liability, if any, imposed by this chapter for the taxable year in which the credit is properly claimed.
(b) In the case of a partnership, S corporation, estate, or trust, the tax credit allowable shall be for qualified expenses incurred by the entity for the taxable year. The expenses upon which the tax credit is computed shall be determined at the entity level. Distribution and share of credit shall be determined by rule.
(c) The safe room installation income tax credit shall be equal to per cent of the taxpayer's qualified expenses, up to a maximum of $ .
(d) The total amount of tax credits allowed under this section shall not exceed $ for all taxpayers in any taxable year; provided that any taxpayer who is ineligible to claim the credit in a taxable year due to the $ cap having been exceeded for that taxable year shall be eligible to claim the credit in the subsequent taxable year.
(e) The director of taxation:
(1) Shall prepare any forms that may be necessary to claim a tax credit under this section;
(2) Shall require the taxpayer to furnish reasonable information to verify the claim for the tax credit made under this section, including but not limited to requiring the taxpayer to provide a certification from an architect or structural engineer licensed to practice in the State certifying that the completed safe room or safe rooms satisfy the minimum specifications established by this section; and
(3) May adopt rules under chapter 91 necessary to effectuate the purposes of this section.
(f) The credit allowed under this section shall be claimed against the net income tax liability for the taxable year. If the tax credit under this section exceeds the taxpayer's income tax liability, the excess of the tax credit over liability may be used as a credit against the taxpayer's net income tax liability in subsequent years until exhausted. All claims, including amended claims, for a tax credit under this section shall be filed on or before the end of the twelfth month following the close of the taxable year for which the credit may be claimed. Failure to comply with the foregoing provision shall constitute a waiver of the right to claim the credit.
(g) For the purposes of this section:
"Qualified expenses" means costs that are necessary and directly incurred by the taxpayer for the design, materials, installation, and construction of one or more safe rooms located on the taxpayer's property.
"Safe room" means a windowless room within a residence or within an accessory building to a residence, designed and constructed to resist the effects of wind pressures and to resist impact from windborne debris; provided that the room:
(1) Is not located in a flood zone, storm surge, or other area susceptible to flooding;
(2) Is readily accessible to persons residing within the residence; and
(3) Is designed and constructed pursuant to hurricane standards that are, at a minimum, in compliance with:
(A) Federal Emergency Management Agency Publication 320 "Taking Shelter from the Storm: Building or Installing a Safe Room for Your Home", March 2021 edition, as amended; and
(B) Federal Emergency Management Agency Publication 361 "Safe Rooms for Tornadoes and Hurricanes: Guidance for Community and Residential Safe Rooms", April 2021 edition, as amended."
SECTION 2. New statutory material is underscored.
SECTION 3. This Act, upon its approval, shall apply to taxable years beginning after December 31, 2024.
|
INTRODUCED BY: |
_____________________________ |
|
|
|
|
|
|
|
|
|
Report Title:
Income Tax Credit; Safe Room Installation Income Tax Credit; Hurricane-Resistant Safe Rooms; Director of Taxation
Description:
Establishes a nonrefundable income tax credit for taxpayers that incur costs related to the design, materials, installation, and construction of hurricane-resistant safe rooms.
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
Date
|
Status
|
|---|---|
| Dec 8, 2025 | Carried over to 2026 Regular Session. |
| Feb 5, 2025 | Report adopted; Passed Second Reading, as amended (SD 1) and referred to WAM. |
| Feb 5, 2025 | Reported from PSM (Stand. Com. Rep. No. 34) with recommendation of passage on Second Reading, as amended (SD 1) and referral to WAM. |
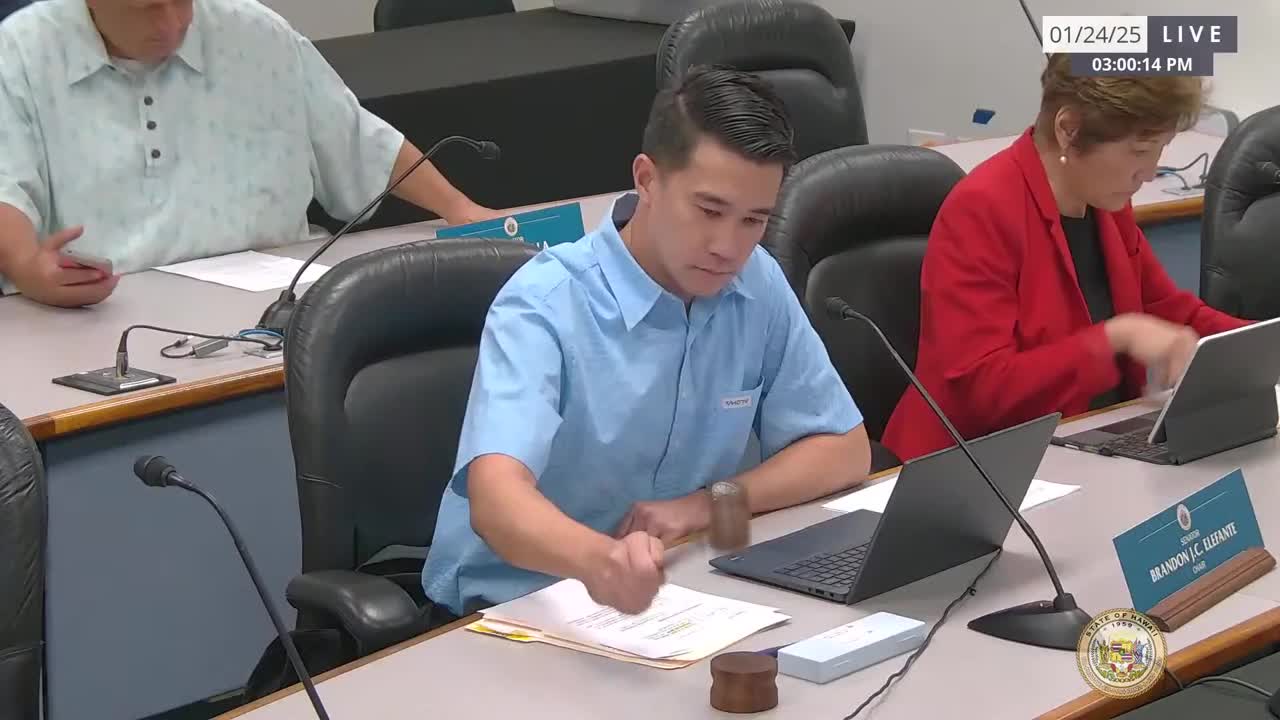
| Jan 24, 2025 | The committee(s) on PSM recommend(s) that the measure be PASSED, WITH AMENDMENTS. The votes in PSM were as follows: 4 Aye(s): Senator(s) Elefante, Wakai, Fukunaga, Rhoads; Aye(s) with reservations: none ; 1 No(es): Senator(s) DeCorte; and 0 Excused: none. |
| Jan 21, 2025 | The committee(s) on PSM has scheduled a public hearing on 01-24-25 3:00PM; Conference Room 225 & Videoconference. |
| Jan 17, 2025 | Referred to PSM, WAM. |
| Jan 15, 2025 | Introduced and passed First Reading. |
| Jan 10, 2025 | Pending Introduction. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Jan 24, 2025 | The committee(s) on PSM recommend(s) that the measure be PASSED, WITH AMENDMENTS | Senate Standing Committee on Public Safety and Military Affairs |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
STAND. COM. REP. NO. 34
Honolulu, Hawaii
RE: S.B. No. 138
S.D. 1
Honorable Ronald D. Kouchi
President of the Senate
Thirty-Third State Legislature
Regular Session of 2025
State of Hawaii
Sir:
Your Committee on Public Safety and Military Affairs, to which was referred S.B. No. 138 entitled:
"A BILL FOR AN ACT RELATING TO TAXATION,"
begs leave to report as follows:
The purpose and intent of this measure is to establish a nonrefundable income tax credit for installation expenses of hurricane-resistant safe rooms.
Your Committee received comments on this measure from the Department of Taxation, Hawaiʻi Emergency Management Agency, and Tax Foundation of Hawaii.
Your Committee finds that hurricanes and similar natural disasters pose a significant threat to the safety of residents of the State. The Federal Emergency Management Agency has published guidance for building or installing safe rooms in homes as a means to protect people from these natural disasters, but the total costs of creating these safe rooms may be prohibitively expensive for Hawaii residents. Your Committee further finds that easing residents' abilities to construct hurricane-resistant "safe rooms" is a potential way to increase the community's safety. This measure will therefore assist residents in affording the process of constructing safe rooms in their homes by establishing a nonrefundable income tax credit for taxpayers that incur costs related to the design, materials, installation, and construction of hurricane-resistant safe rooms.
Your Committee has amended this measure by:
(1) Specifying that no other tax credit or deduction shall be claimed State income tax law for qualified expenses for the taxable year; and
(2) Inserting an effective date of July 1, 2077, to encourage further discussion.
As affirmed by the record of votes of the members of your Committee on Public Safety and Military Affairs that is attached to this report, your Committee is in accord with the intent and purpose of S.B. No. 138, as amended herein, and recommends that it pass Second Reading in the form attached hereto as S.B. No. 138, S.D. 1, and be referred to your Committee on Ways and Means.
Respectfully submitted on behalf of the members of the Committee on Public Safety and Military Affairs,
|
|
|
________________________________ BRANDON J.C. ELEFANTE, Chair |
|
|
|
|
Discussed in Hearing
 2MIN
Senate Standing Committee on Public Safety and Military Affairs
Bill Author
Bill Co-Author(s):