HB 1173: Taxation; DOTAX; Tax Liens; Discharge When Unenforceable
- Session Year: 2025-2026
- House: House
- Latest Version Date: 2025-04-26
Current Status:
In Progress
(2025-05-19: Act 068, on 05/19/2025 (Gov. Msg. No. 1168).)
Introduced
In Committee
First Chamber
In Committee
Second Chamber
Final Decking
Enacted
What does this bill do?
The bill requires the Department of Taxation to show the assessment date on tax lien certificates and to issue a certificate that clears a lien when the underlying tax has been paid or is no longer collectible. It affects taxpayers with recorded state tax liens by providing a formal way to remove liens that have been satisfied or become unenforceable because the time limit to collect has passed.
The summary is provided by generative AI which can make mistakes. For original language, please view the details in the table below.
Requires the Department of Taxation to: (1) State the assessment date on certificates of tax lien; and (2) Issue certificates of discharge when the tax liability on which a lien is based has been satisfied or has become unenforceable by lapse of time. Effective 1/1/2027. (CD1)
Requires the Department of Taxation to: (1) State the assessment date on certificates of tax lien; and (2) Issue certificates of discharge when the tax liability on which a lien is based has been satisfied or has become unenforceable by lapse of time. Effective 7/1/3000. (SD1)
Requires the Department of Taxation to: (1) State the assessment date on certificates of tax lien; and (2) Issue certificates of discharge when the tax liability on which a lien is based has been satisfied or has become unenforceable by lapse of time. Effective 7/1/3000. (HD1)
Requires the Department of Taxation to: (1) State the assessment date on certificates of tax lien; and (2) Issue certificates of discharge when the tax liability on which a lien is based has become unenforceable by lapse of time.
|
HOUSE OF REPRESENTATIVES |
H.B. NO. |
1173 |
|
THIRTY-THIRD LEGISLATURE, 2025 |
H.D. 1 |
|
|
STATE OF HAWAII |
S.D. 1 |
|
|
|
C.D. 1 |
|
|
|
||
|
|
||
A BILL FOR AN ACT
RELATING TO TAX LIENS.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
SECTION 1. The legislature finds that Act 166, Session Laws of Hawaii 2009, enacted a fifteen-year statute of limitations on certain collection actions of tax assessments, comparable to the ten-year statute of limitations that applies to federal taxes.
The purpose of this Act is to adopt procedures comparable to those in the federal system to ensure that taxpayers are not harmed by previously recorded tax liens for which the underlying liability has been satisfied or been rendered unenforceable by the expiration of the fifteen-year period.
SECTION 2. Section 231-33, Hawaii Revised Statutes, is amended by amending subsections (f) and (g) to read as follows:
"(f) The department may record in the bureau of
conveyances at Honolulu, or in respect of a lien on a motor vehicle, file with
the county director of finance, a certificate setting forth the amount of taxes
due and unpaid, which have been returned, assessed, or as to which a notice of
proposed assessment has issued. The
certificate shall identify the taxpayer, the taxpayer's last known address, [and]
the tax or taxes involved[.], and the date on which the liability for
the tax or taxes was assessed. The recording
or filing of the certificate has the effect set forth in this section, but
nothing in this section shall be deemed to require that a certificate recorded
or filed by the department must include the amount of any penalty or interest,
in order to protect the lien therefor.
The certificate, if recorded or filed with the county director of
finance, shall be entered of record as provided by law. Recordation of the certificate in the bureau
of conveyances shall be deemed, at such time, for all purposes and without any
further action, to procure a lien on land registered in the land court under
chapter 501. Any cost incurred in the
filing of the certificate shall be a part of the lien for the tax therein set
forth.
(g) The department may issue a certificate of
discharge of any part of the property subject to the lien imposed by this
section, upon payment in partial satisfaction of such lien, of an amount not
less than the value as determined by the department of the lien on the part to
be so discharged, or if the department determines that the lien on the part to
be discharged has no value. The
department shall issue a certificate of discharge as to any liability that has
been satisfied or that has become unenforceable under section 235‑111,
237-40, 237D-9, 238-7, 243-14, 247-6.5, or 251-8. Any [such] discharge so issued shall
be conclusive evidence of the discharge of the lien as therein provided."
SECTION 3. Statutory material to be repealed is bracketed and stricken. New statutory material is underscored.
SECTION 4. This Act shall take effect on January 1, 2027.
Report Title:
Taxation; DOTAX; Tax Liens; Discharge When Unenforceable
Description:
Requires the Department of Taxation to: (1) State the assessment date on certificates of tax lien; and (2) Issue certificates of discharge when the tax liability on which a lien is based has been satisfied or has become unenforceable by lapse of time. Effective 1/1/2027. (CD1)
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
HOUSE OF REPRESENTATIVES |
H.B. NO. |
1173 |
|
THIRTY-THIRD LEGISLATURE, 2025 |
H.D. 1 |
|
|
STATE OF HAWAII |
S.D. 1 |
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
RELATING TO TAX LIENS.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
SECTION 1. The legislature finds that Act 166, Session Laws of Hawaii 2009, enacted a fifteen-year statute of limitations on certain collection actions of tax assessments, comparable to the ten-year statute of limitations that applies to federal taxes.
The purpose of this Act is to adopt procedures comparable to those in the federal system to ensure that taxpayers are not harmed by previously recorded tax liens for which the underlying liability has been satisfied or been rendered unenforceable by the expiration of the fifteen-year period.
SECTION 2. Section 231-33, Hawaii Revised Statutes, is amended by amending subsections (f) and (g) to read as follows:
"(f) The department may record in the bureau of
conveyances at Honolulu, or in respect of a lien on a motor vehicle, file with
the county director of finance, a certificate setting forth the amount of taxes
due and unpaid, which have been returned, assessed, or as to which a notice of
proposed assessment has issued. The
certificate shall identify the taxpayer, the taxpayer's last known address, [and]
the tax or taxes involved[.], and the date on which the liability for
the tax or taxes was assessed. The recording
or filing of the certificate has the effect set forth in this section, but
nothing in this section shall be deemed to require that a certificate recorded
or filed by the department must include the amount of any penalty or interest,
in order to protect the lien therefor.
The certificate, if recorded or filed with the county director of
finance, shall be entered of record as provided by law. Recordation of the certificate in the bureau
of conveyances shall be deemed, at such time, for all purposes and without any
further action, to procure a lien on land registered in the land court under
chapter 501. Any cost incurred in the
filing of the certificate shall be a part of the lien for the tax therein set
forth.
(g) The department may issue a certificate of
discharge of any part of the property subject to the lien imposed by this
section, upon payment in partial satisfaction of such lien, of an amount not
less than the value as determined by the department of the lien on the part to
be so discharged, or if the department determines that the lien on the part to
be discharged has no value. The
department shall issue a certificate of discharge as to any liability that has
been satisfied or that has become unenforceable under section 235‑111,
237-40, 237D-9, 238-7, 243-14, 247-6.5, or 251-8. Any [such] discharge so issued shall
be conclusive evidence of the discharge of the lien as therein provided."
SECTION 3. Statutory material to be repealed is bracketed and stricken. New statutory material is underscored.
SECTION 4. This Act shall take effect on July 1, 3000.
Report Title:
Taxation; DOTAX; Tax Liens; Discharge When Unenforceable
Description:
Requires the Department of Taxation to: (1) State the assessment date on certificates of tax lien; and (2) Issue certificates of discharge when the tax liability on which a lien is based has been satisfied or has become unenforceable by lapse of time. Effective 7/1/3000. (SD1)
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
HOUSE OF REPRESENTATIVES |
H.B. NO. |
1173 |
|
THIRTY-THIRD LEGISLATURE, 2025 |
H.D. 1 |
|
|
STATE OF HAWAII |
|
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
RELATING TO TAX LIENS.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
SECTION 1. The legislature finds that Act 166, Session Laws of Hawaii 2009, enacted a fifteen-year statute of limitations on certain collection actions of tax assessments, comparable to the ten-year statute of limitations that applies to federal taxes.
The purpose of this Act is to adopt procedures comparable to those in the federal system to ensure that taxpayers are not harmed by previously recorded tax liens for which the underlying liability has been satisfied or been rendered unenforceable by the expiration of the fifteen-year period.
SECTION 2. Section 231-33, Hawaii Revised Statutes, is amended by amending subsections (f) and (g) to read as follows:
"(f) The department may record in the bureau of
conveyances at Honolulu, or in respect of a lien on a motor vehicle, file with
the county director of finance, a certificate setting forth the amount of taxes
due and unpaid, which have been returned, assessed, or as to which a notice of
proposed assessment has issued. The
certificate shall identify the taxpayer, the taxpayer's last known address, [and]
the tax or taxes involved[.], and the date on which the liability for
the tax or taxes was assessed. The recording
or filing of the certificate has the effect set forth in this section, but
nothing in this section shall be deemed to require that a certificate recorded
or filed by the department must include the amount of any penalty or interest,
in order to protect the lien therefor.
The certificate, if recorded or filed with the county director of
finance, shall be entered of record as provided by law. Recordation of the certificate in the bureau
of conveyances shall be deemed, at such time, for all purposes and without any
further action, to procure a lien on land registered in the land court under
chapter 501. Any cost incurred in the
filing of the certificate shall be a part of the lien for the tax therein set
forth.
(g) The department may issue a certificate of
discharge of any part of the property subject to the lien imposed by this
section, upon payment in partial satisfaction of such lien, of an amount not
less than the value as determined by the department of the lien on the part to
be so discharged, or if the department determines that the lien on the part to
be discharged has no value. The
department shall issue a certificate of discharge as to any liability that has
been satisfied or that has become unenforceable under sections 235-111, 237-40,
237D-9, 238-7, 243-14, 247-6.5, 251-8, and 431:7-204.6. Any [such] discharge so issued shall
be conclusive evidence of the discharge of the lien as therein provided."
SECTION 3. Statutory material to be repealed is bracketed and stricken. New statutory material is underscored.
SECTION 4. This Act shall take effect on July 1, 3000.
Report Title:
Taxation; DOTAX; Tax Liens; Discharge When Unenforceable
Description:
Requires the Department of Taxation to: (1) State the assessment date on certificates of tax lien; and (2) Issue certificates of discharge when the tax liability on which a lien is based has been satisfied or has become unenforceable by lapse of time. Effective 7/1/3000. (HD1)
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
HOUSE OF REPRESENTATIVES |
H.B. NO. |
1173 |
|
THIRTY-THIRD LEGISLATURE, 2025 |
|
|
|
STATE OF HAWAII |
|
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
RELATING TO TAX LIENS.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
SECTION 1. The legislature finds that Act 166, Session Laws of Hawaii 2009, enacted a fifteen-year statute of limitations on the collection of taxes that had been timely assessed, comparable to the ten-year statute of limitations that applies to federal taxes.
The purpose of this Act is to adopt procedures comparable to those in the federal system to ensure that taxpayers are not harmed by previously recorded tax liens for which the underlying liability has been rendered unenforceable by the expiration of the fifteen-year period.
SECTION 2. Section 231-33, Hawaii Revised Statutes, is amended by amending subsections (f) and (g) to read as follows:
"(f) The department may record in the bureau of
conveyances at Honolulu, or in respect of a lien on a motor vehicle, file with
the county director of finance, a certificate setting forth the amount of taxes
due and unpaid, which have been returned, assessed, or as to which a notice of
proposed assessment has issued. The
certificate shall identify the taxpayer, the taxpayer's last known address, [and]
the tax or taxes involved[.], and the date on which the liability for
the tax or taxes was assessed. The
recording or filing of the certificate has the effect set forth in this
section, but nothing in this section shall be deemed to require that a
certificate recorded or filed by the department must include the amount of any
penalty or interest, in order to protect the lien therefor. The certificate, if recorded or filed with
the county director of finance, shall be entered of record as provided by law. Recordation of the certificate in the bureau
of conveyances shall be deemed, at such time, for all purposes and without any
further action, to procure a lien on land registered in the land court under
chapter 501. Any cost incurred in the
filing of the certificate shall be a part of the lien for the tax therein set
forth.
(g) The department may issue a certificate of
discharge of any part of the property subject to the lien imposed by this
section, upon payment in partial satisfaction of such lien, of an amount not
less than the value as determined by the department of the lien on the part to
be so discharged, or if the department determines that the lien on the part to
be discharged has no value. The
department shall issue a certificate of discharge as to any liability that has
been satisfied or that has become unenforceable. Any [such] discharge so issued shall
be conclusive evidence of the discharge of the lien as therein provided."
SECTION 3. Statutory material to be repealed is bracketed and stricken. New statutory material is underscored.
SECTION 4. This Act shall take effect upon its approval.
|
INTRODUCED BY: |
_____________________________ |
|
|
|
Report Title:
Taxation; DOTAX; Tax Liens; Discharge When Unenforceable
Description:
Requires the Department of Taxation to: (1) State the assessment date on certificates of tax lien; and (2) Issue certificates of discharge when the tax liability on which a lien is based has become unenforceable by lapse of time.
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
Date
|
Status
|
|---|---|
| May 19, 2025 | Act 068, on 05/19/2025 (Gov. Msg. No. 1168). |
| May 19, 2025 | Act 068, 05/19/2025 (Gov. Msg. No. 1168). |
| May 1, 2025 | Transmitted to Governor. |
| May 2, 2025 | Received notice of passage on Final Reading in House (Hse. Com. No. 821). |
| May 1, 2025 | Received notice of Final Reading (Sen. Com. No. 888). |
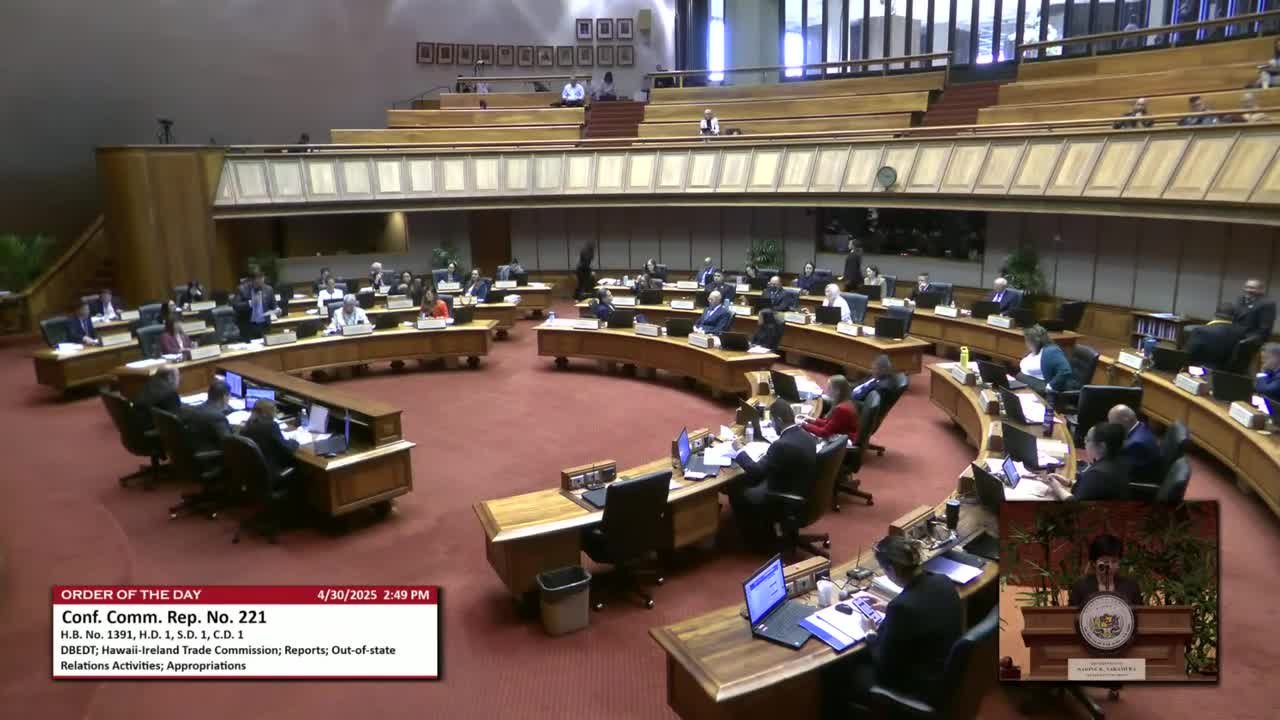
| Apr 30, 2025 | Passed Final Reading as amended in CD 1 with none voting aye with reservations; Representative(s) Iwamoto voting no (1) and Representative(s) Cochran excused (1). |
| Apr 30, 2025 | Passed Final Reading, as amended (CD 1). Ayes, 25; Aye(s) with reservations: none . 0 No(es): none. 0 Excused: none. |
| Apr 25, 2025 | 48 Hrs. Notice (as amended CD 1) 04-30-25 |
| Apr 25, 2025 | Reported from Conference Committee as amended CD 1 (Conf. Com. Rep. No. 246). |
| Apr 25, 2025 | Forty-eight (48) hours notice Wednesday, 04-30-25. |
| Apr 25, 2025 | Reported from Conference Committee (Conf Com. Rep. No. 246) as amended in (CD 1). |
| Apr 23, 2025 | The Conference committee recommends that the measure be PASSED, WITH AMENDMENTS. The votes of the Senate Conference Managers were as follows: 3 Aye(s): Senator(s) Kim, Moriwaki, Fevella; Aye(s) with reservations: none ; 0 No(es): none; and 0 Excused: none. |
| Apr 23, 2025 | The Conference Committee recommends that the measure be Passed, with Amendments. The votes were as follows: 3 Ayes: Representative(s) Yamashita, Takenouchi, Alcos; Ayes with reservations: none; 0 Noes: none; and 0 Excused: none. |
| Apr 22, 2025 | Bill scheduled for Conference Committee Meeting on Wednesday, 04-23-25 10:30AM in conference room 309. |
| Apr 15, 2025 | Received notice of Senate conferees (Sen. Com. No. 788). |
| Apr 15, 2025 | Senate Conferees Appointed: Kim Chair; Moriwaki, Fevella. |
| Apr 15, 2025 | Received notice of appointment of House conferees (Hse. Com. No. 732). |
| Apr 14, 2025 | House Conferees Appointed: Yamashita Chair; Takenouchi, Alcos. |
| Apr 11, 2025 | Received notice of disagreement (Hse. Com. No. 704). |
| Apr 10, 2025 | House disagrees with Senate amendment (s). |
| Apr 8, 2025 | Returned from Senate (Sen. Com. No. 747) in amended form (SD 1). |
| Apr 8, 2025 | Passed Third Reading, as amended (SD 1). Ayes, 25; Aye(s) with reservations: none . Noes, 0 (none). Excused, 0 (none). Transmitted to House. |
| Apr 4, 2025 | 48 Hrs. Notice 04-08-25. |
| Apr 4, 2025 | Report adopted; Passed Second Reading, as amended (SD 1). |
| Apr 4, 2025 | Reported from WAM (Stand. Com. Rep. No. 1729) with recommendation of passage on Second Reading, as amended (SD 1) and placement on the calendar for Third Reading. |
| Apr 1, 2025 | The committee(s) on WAM recommend(s) that the measure be PASSED, WITH AMENDMENTS. The votes in WAM were as follows: 11 Aye(s): Senator(s) Dela Cruz, Moriwaki, Aquino, Elefante, Hashimoto, Inouye, Kanuha, Kidani, Kim, Lee, C., Fevella; Aye(s) with reservations: none ; 0 No(es): none; and 2 Excused: Senator(s) DeCoite, Wakai. |
| Mar 28, 2025 | The committee(s) on WAM deferred the measure until 04-01-25 10:00AM; Conference Room 211 & Videoconference. |
| Mar 25, 2025 | The committee(s) on WAM has scheduled a public hearing on 03-28-25 10:00AM; Conference Room 211 & Videoconference. |
| Mar 6, 2025 | Referred to WAM. |
| Mar 6, 2025 | Passed First Reading. |
| Mar 6, 2025 | Received from House (Hse. Com. No. 344). |
| Mar 4, 2025 | Passed Third Reading with none voting aye with reservations; none voting no (0) and Representative(s) Pierick, Ward excused (2). Transmitted to Senate. |
| Feb 28, 2025 | Passed Second Reading as amended in HD 1; placed on the calendar for Third Reading with none voting aye with reservations; none voting no (0) and Representative(s) Cochran, Pierick, Templo, Ward excused (4). |
| Feb 28, 2025 | Reported from FIN (Stand. Com. Rep. No. 993) as amended in HD 1, recommending passage on Second Reading and placement on the calendar for Third Reading. |
| Feb 19, 2025 | The committee on FIN recommend that the measure be PASSED, WITH AMENDMENTS. The votes were as follows: 12 Ayes: Representative(s) Yamashita, Takenouchi, Holt, Hussey, Kitagawa, Kusch, Lamosao, Lee, M., Miyake, Morikawa, Templo, Reyes Oda; Ayes with reservations: none; Noes: none; and 4 Excused: Representative(s) Grandinetti, Keohokapu-Lee Loy, Alcos, Ward. |
| Feb 14, 2025 | Bill scheduled to be heard by FIN on Wednesday, 02-19-25 2:00PM in House conference room 308 VIA VIDEOCONFERENCE. |
| Jan 27, 2025 | Referred to FIN, referral sheet 4 |
| Jan 23, 2025 | Introduced and Pass First Reading. |
| Jan 21, 2025 | Pending introduction. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Apr 30, 2025 | Final Reading | House Floor |
Passed |
|
| Apr 30, 2025 | Final Reading | Senate Floor |
Passed |
|
| Apr 8, 2025 | Third Reading | Senate Floor |
Passed |
|
| Apr 1, 2025 | The committee(s) on WAM recommend(s) that the measure be PASSED, WITH AMENDMENTS | Senate Standing Committee on Ways and Means |
Passed |
|
| Mar 4, 2025 | Third Reading | House Floor |
Passed |
|
| Feb 19, 2025 | The committee on FIN recommend that the measure be PASSED, WITH AMENDMENTS | House Standing Committee on Finance |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| Chamber of Commerce Hawaii | ** Support | |
| Hawaii Association of Public Accountants | *** Support | Feb 19, 2025 |
CONFERENCE COMMITTEE REP. NO. 246
Honolulu, Hawaii
, 2025
RE: H.B. No. 1173
H.D. 1
S.D. 1
C.D. 1
Honorable Nadine K. Nakamura
Speaker, House of Representatives
Thirty-Third State Legislature
Regular Session of 2025
State of Hawaii
Honorable Ronald D. Kouchi
President of the Senate
Thirty-Third State Legislature
Regular Session of 2025
State of Hawaii
Madam and Sir:
Your Committee on Conference on the disagreeing vote of the House of Representatives to the amendments proposed by the Senate in H.B. No. 1173, H.D. 1, S.D. 1, entitled:
"A BILL FOR AN ACT RELATING TO TAX LIENS,"
having met, and after full and free discussion, has agreed to recommend and does recommend to the respective Houses the final passage of this bill in an amended form.
The purpose of this measure is to require the Department of Taxation to:
(1) State the assessment date on certificates of tax lien; and
(2) Issue certificates of discharge when the tax liability on which a lien is based has been satisfied or has become unenforceable by lapse of time.
Your Committee on Conference has amended this measure by changing the effective date to January 1, 2027.
As affirmed by the record of votes of the managers of your Committee on Conference that is attached to this report, your Committee on Conference is in accord with the intent and purpose of H.B. No. 1173, H.D. 1, S.D. 1, as amended herein, and recommends that it pass Final Reading in the form attached hereto as H.B. No. 1173, H.D. 1, S.D. 1, C.D. 1.
Respectfully submitted on behalf of the managers:
|
ON THE PART OF THE SENATE |
|
ON THE PART OF THE HOUSE |
|
____________________________ DONNA MERCADO KIM Chair |
|
____________________________ KYLE T. YAMASHITA Chair |
|
|
|
|
|
|
|
|
|
|
|
|
STAND. COM. REP. NO. 1729
Honolulu, Hawaii
RE: H.B. No. 1173
H.D. 1
S.D. 1
Honorable Ronald D. Kouchi
President of the Senate
Thirty-Third State Legislature
Regular Session of 2025
State of Hawaii
Sir:
Your Committee on Ways and Means, to which was referred H.B. No. 1173, H.D. 1, entitled:
"A BILL FOR AN ACT RELATING TO TAX LIENS,"
begs leave to report as follows:
The purpose and intent of this measure is to clarify the State's laws regarding tax liens.
More specifically, the measure requires the Department of Taxation to:
(1) State the assessment date on certificates of tax lien; and
(2) Issue certificates of discharge when the tax liability upon which a lien is based has been satisfied or has become unenforceable by lapse of time.
Your Committee received testimony in support of this measure from the Chamber of Commerce Hawaii and one individual.
Your Committee received comments on this measure from the Department of Taxation and Tax Foundation of Hawaii.
Your Committee finds that providing a clear and reliable procedure for extinguishing tax liens once the underlying liability is paid in full or becomes unenforceable will promote transparency, safeguard taxpayers from undue tax burdens, and streamline the State's tax administration.
Your Committee has amended this measure by:
(1) Deleting the application of the measure to section 431:7-204.6, Hawaii Revised Statutes, as recommended by the Department of Taxation; and
(2) Making technical, nonsubstantive edits for purposes of clarity, consistency, and style.
As affirmed by the record of votes of the members of your Committee on Ways and Means that is attached to this report, your Committee is in accord with the intent and purpose of H.B. No. 1173, H.D. 1, as amended herein, and recommends that it pass Second Reading in the form attached hereto as H.B. No. 1173, H.D. 1, S.D. 1, and be placed on the calendar for Third Reading.
Respectfully submitted on behalf of the members of the Committee on Ways and Means,
|
|
|
________________________________ DONOVAN M. DELA CRUZ, Chair |
|
|
|
|
STAND. COM. REP. NO. 993
Honolulu, Hawaii
, 2025
RE: H.B. No. 1173
H.D. 1
Honorable Nadine K. Nakamura
Speaker, House of Representatives
Thirty-Third State Legislature
Regular Session of 2025
State of Hawaii
Madame:
Your Committee on Finance, to which was referred H.B. No. 1173 entitled:
"A BILL FOR AN ACT RELATING TO TAX LIENS,"
begs leave to report as follows:
The purpose of this measure is to require the Department of Taxation to:
(1) State the assessment date on certificates of tax liens; and
(2) Issue certificates of discharge when the tax liability on which a lien is based has been satisfied or has become unenforceable by lapse of time.
Your Committee finds that Act 166, Session Laws of Hawaii 2009, created a fifteen-year statute of limitations on certain collection actions on tax assessments, specifically by prohibiting a levy or proceeding in court under chapter 231, Hawaii Revised Statutes, to collect tax if the levy or proceeding is initiated after the fifteen-year period. By requiring the inclusion of the tax liability assessment date on tax lien certificates and requiring the Department of Taxation to issue a certificate of discharge for satisfied or unenforceable liabilities, this measure would, among other things, inform taxpayers of how much time they have to pay off the liability and may better align state tax collection practices with federal practices.
Your Committee further finds that certain sections of state law relating to income tax, general excise tax, transient accommodations tax, use tax, fuel tax, conveyance tax, rental motor vehicle and tour vehicle surcharge tax, and insurance tax contain provisions that may suspend or extend the fifteen-year statute of limitations on collection after assessment. Your Committee believes that this measure should be clarified to require the Department of Taxation to issue certificates of discharge for liabilities that have been satisfied or have become unenforceable under those sections.
Accordingly, your Committee has amended this measure by:
(1) Clarifying the applicable taxes that are subject to the fifteen-year statute of limitations imposed by Act 166, Session Laws of Hawaii 2009;
(2) Changing the effective date to July 1, 3000, to encourage further discussion; and
(3) Making technical, nonsubstantive amendments for the purposes of clarity, consistency, and style.
As affirmed by the record of votes of the members of your Committee on Finance that is attached to this report, your Committee is in accord with the intent and purpose of H.B. No. 1173, as amended herein, and recommends that it pass Second Reading in the form attached hereto as H.B. No. 1173, H.D. 1, and be placed on the calendar for Third Reading.
Respectfully submitted on behalf of the members of the Committee on Finance,
|
|
|
____________________________ KYLE T. YAMASHITA, Chair |
|
|
|
|
|
Date
|
Testimony PDF
|
|---|---|
| Mar 27, 2025 | HB1173_HD1_TESTIMONY_WAM_03-28-25_.PDF |
| Feb 19, 2025 | HB1173_TESTIMONY_FIN_02-19-25_.PDF |
Discussed in Hearing
 1MIN
House Floor
 1MIN
Conference Committee
 2MIN
Senate Standing Committee on Education
2MIN
Senate Standing Committee on Government Operations
2MIN
Senate Standing Committee on Ways and Means
 5MIN
House Standing Committee on Finance
Bill Author
Bill Co-Author(s):