HB 1851: Taxation; Apprenticeship Program Income Tax Credit; Qualified Apprenticeship Program; Qualified Costs
- Session Year: 2025-2026
- House: House
- Latest Version Date: 2026-03-06
Current Status:
Failed
(2026-03-12: Referred to WAM.)
Introduced
In Committee
First Chamber
In Committee
Second Chamber
Final Decking
Enacted
What does this bill do?
Creates a new income tax credit for taxpayers who pay wages to apprentices in Hawaii-registered apprenticeship programs. The credit equals up to $4,800 or 50% of the apprentice wages in a year (whichever is less), is subject to per-program and statewide yearly caps, may be claimed for the same program for up to two years, and any excess credit can be used in later years. Claimants must submit a certified statement from the Department of Labor and Industrial Relations and cannot claim another tax credit for the same apprentice wages.
The summary is provided by generative AI which can make mistakes. For original language, please view the details in the table below.
Establishes an apprenticeship program income tax credit for certain qualified costs incurred by a taxpayer for a qualified apprenticeship program. Sunsets 12/31/2036. Effective 7/1/3000. (HD3)
Establishes an apprenticeship program income tax credit for certain qualified costs incurred by a taxpayer for a qualified apprenticeship program. Sunsets 12/31/2036. Effective 7/1/3000. (HD2)
Establishes an apprenticeship program income tax credit for certain qualified costs incurred by a qualified apprenticeship program. Contains an unspecified sunset date. Effective 7/1/3000. (HD1)
Establishes an apprenticeship program income tax credit for certain qualified costs incurred by a qualified apprenticeship program. Applies to taxable years beginning after 12/31/2025.
|
HOUSE OF REPRESENTATIVES |
H.B. NO. |
1851 |
|
THIRTY-THIRD LEGISLATURE, 2026 |
H.D. 3 |
|
|
STATE OF HAWAII |
|
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
RELATING TO TAXATION.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
SECTION 1. Chapter 235, Hawaii Revised Statutes, is amended by adding a new section to part VI to be appropriately designated and to read as follows:
"§235- Apprenticeship program income tax credit. (a) There shall be allowed to each taxpayer subject to the taxes imposed by this chapter an apprenticeship program income tax credit that shall be deductible from the taxpayer's net income tax liability, if any, imposed by this chapter for the taxable year in which the credit is properly claimed.
(b) The amount of the tax credit shall be $4,800 or fifty per cent of the qualified costs, whichever is less, incurred by the taxpayer for a qualified apprenticeship program in the taxable year; provided that:
(1) The total tax credit claimed per qualified apprenticeship program shall not exceed $ per taxable year; and
(2) The aggregate amount of tax credits allowed under this section shall not exceed $ for all taxpayers in any taxable year; provided that any taxpayer who is not eligible to claim the credit in a taxable year due to the $ cap having been exceeded for that taxable year shall be eligible to claim the credit in the subsequent taxable year.
The taxpayer may apply the credit for the same qualified apprenticeship program for up to two consecutive taxable years.
(c) If the tax credit under this section exceeds the taxpayer's income tax liability, the excess of the credit over liability may be used as a credit against the taxpayer's income tax liability in subsequent years until exhausted. All claims for the tax credit under this section, including amended claims, shall be filed on or before the end of the twelfth month following the close of the taxable year for which the credit may be claimed. Failure to comply with this provision shall constitute a waiver of the right to claim the credit.
(d) To qualify for the income tax credit, the taxpayer shall be in compliance with all applicable federal, state, and county statutes, ordinances, rules, and regulations.
(e) Every taxpayer claiming a tax credit under this section shall file with the department of taxation a written, certified statement from the department of labor and industrial relations verifying that the apprenticeship program is a qualified apprenticeship program and specifying the amount of qualified costs incurred.
(f) The director of taxation:
(1) Shall prepare any forms necessary to claim a credit under this section;
(2) May require the taxpayer to furnish information to ascertain the validity of the claim for credit made under this section; and
(3) May adopt rules under chapter 91 necessary to effectuate the purposes of this section.
(g) No taxpayer that claims a credit under this section shall claim any other credit for the same qualified costs under this chapter.
(h) As used in this section:
"Qualified apprenticeship program" means an apprenticeship program in the State that is registered and approved by the department of labor and industrial relations.
"Qualified costs" means the wages paid to each apprentice."
SECTION 2. New statutory material is underscored.
SECTION 3. This Act shall take effect on July 1, 3000; provided that this Act:
(1) Shall apply to taxable years beginning after December 31, 2025; and
(2) Shall be repealed on December 31, 2036.
Report Title:
Taxation; Apprenticeship Program Income Tax Credit; Qualified Apprenticeship Program; Qualified Costs
Description:
Establishes an apprenticeship program income tax credit for certain qualified costs incurred by a taxpayer for a qualified apprenticeship program. Sunsets 12/31/2036. Effective 7/1/3000. (HD3)
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
HOUSE OF REPRESENTATIVES |
H.B. NO. |
1851 |
|
THIRTY-THIRD LEGISLATURE, 2026 |
H.D. 2 |
|
|
STATE OF HAWAII |
|
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
RELATING TO TAXATION.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
SECTION 1. Chapter 235, Hawaii Revised Statutes, is amended by adding a new section to part VI to be appropriately designated and to read as follows:
"§235- Apprenticeship program income tax credit. (a) There shall be allowed to each taxpayer subject to the taxes imposed by this chapter an apprenticeship program income tax credit that shall be deductible from the taxpayer's net income tax liability, if any, imposed by this chapter for the taxable year in which the credit is properly claimed.
(b) The amount of the tax credit shall be $4,800 or fifty per cent of the qualified costs, whichever is less, incurred by the taxpayer for a qualified apprenticeship program in the taxable year; provided that:
(1) The total tax credit claimed per qualified apprenticeship program shall not exceed $ per taxable year; and
(2) The aggregate amount of tax credits allowed under this section shall not exceed $1,500,000 for all taxpayers in any taxable year; provided that any taxpayer who is not eligible to claim the credit in a taxable year due to the $1,500,000 cap having been exceeded for that taxable year shall be eligible to claim the credit in the subsequent taxable year.
The taxpayer may apply the credit for the same qualified apprenticeship program for up to two consecutive taxable years.
(c) If the tax credit under this section exceeds the taxpayer's income tax liability, the excess of the credit over liability may be used as a credit against the taxpayer's income tax liability in subsequent years until exhausted. All claims for the tax credit under this section, including amended claims, shall be filed on or before the end of the twelfth month following the close of the taxable year for which the credit may be claimed. Failure to comply with this provision shall constitute a waiver of the right to claim the credit.
(d) To qualify for the income tax credit, the taxpayer shall be in compliance with all applicable federal, state, and county statutes, ordinances, rules, and regulations.
(e) Every taxpayer claiming a tax credit under this section shall file with the department of taxation a written, certified statement from the department of labor and industrial relations verifying that the apprenticeship program is a qualified apprenticeship program and specifying the amount of qualified costs incurred.
(f) The director of taxation:
(1) Shall prepare any forms necessary to claim a credit under this section;
(2) May require the taxpayer to furnish information to ascertain the validity of the claim for credit made under this section; and
(3) May adopt rules under chapter 91 necessary to effectuate the purposes of this section.
(g) No taxpayer that claims a credit under this section shall claim any other credit for the same qualified costs under this chapter.
(h) As used in this section:
"Qualified apprenticeship program" means an apprenticeship program in the State that is registered and approved by the department of labor and industrial relations.
"Qualified costs" means the wages paid to each apprentice."
SECTION 2. New statutory material is underscored.
SECTION 3. This Act shall take effect on July 1, 3000; provided that this Act:
(1) Shall apply to taxable years beginning after December 31, 2025; and
(2) Shall be repealed on December 31, 2036.
Report Title:
Taxation; Apprenticeship Program Income Tax Credit; Qualified Apprenticeship Program; Qualified Costs
Description:
Establishes an apprenticeship program income tax credit for certain qualified costs incurred by a taxpayer for a qualified apprenticeship program. Sunsets 12/31/2036. Effective 7/1/3000. (HD2)
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
HOUSE OF REPRESENTATIVES |
H.B. NO. |
1851 |
|
THIRTY-THIRD LEGISLATURE, 2026 |
H.D. 1 |
|
|
STATE OF HAWAII |
|
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
RELATING TO TAXATION.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
SECTION 1. Chapter 235, Hawaii Revised Statutes, is amended by adding a new section to part VI to be appropriately designated and to read as follows:
"§235- Apprenticeship program income tax credit. (a) There shall be allowed to each taxpayer subject to the taxes imposed by this chapter an apprenticeship program income tax credit that shall be deductible from the taxpayer's net income tax liability, if any, imposed by this chapter for the taxable year in which the credit is properly claimed.
(b) The amount of the tax credit shall be $4,800 or fifty per cent of the qualified cost, whichever is less, incurred under a qualified apprenticeship program in the taxable year; provided that:
(1) The total tax credit claimed per qualified apprenticeship program shall not exceed $ per taxable year; and
(2) The aggregate amount of tax credits allowed under this section shall not exceed $ for all taxpayers in any taxable year; provided that any taxpayer who is not eligible to claim the credit in a taxable year due to the $ cap having been exceeded for that taxable year shall be eligible to claim the credit in the subsequent taxable year.
The taxpayer may apply the credit for the same apprentice for up to two consecutive taxable years.
(c) If the tax credit under this section exceeds the taxpayer's income tax liability, the excess of the credit over liability may be used as a credit against the taxpayer's income tax liability in subsequent years until exhausted. All claims for the tax credit under this section, including amended claims, shall be filed on or before the end of the twelfth month following the close of the taxable year for which the credit may be claimed. Failure to comply with this provision shall constitute a waiver of the right to claim the credit.
(d) To qualify for the income tax credit, the taxpayer shall be in compliance with all applicable federal, state, and county statutes, ordinances, rules, and regulations.
(e) Every taxpayer claiming a tax credit under this section shall file with the department of taxation a written, certified statement from the department of labor and industrial relations verifying that the apprenticeship program is a qualified apprenticeship program and specifying the amount of qualified costs incurred.
(f) The director of taxation:
(1) Shall prepare any forms necessary to claim a credit under this section;
(2) May require the taxpayer to furnish information to ascertain the validity of the claim for credit made under this section; and
(3) May adopt rules under chapter 91 necessary to effectuate the purposes of this section.
(g) No taxpayer that claims a credit under this section shall claim any other credit for the same qualified costs under this chapter.
(h) As used in this section:
"Qualified apprenticeship program" means an apprenticeship program in the State that is registered and approved by the department of labor and industrial relations.
"Qualified costs" means the wages paid to each apprentice."
SECTION 2. New statutory material is underscored.
SECTION 3. This Act shall take effect on July 1, 3000; provided that it:
(1) Shall apply to taxable years beginning after December 31, 2025; and
(2) Shall be repealed on December 31, .
Report Title:
Taxation; Apprenticeship Program Income Tax Credit; Qualified Apprenticeship Program; Qualified Costs
Description:
Establishes an apprenticeship program income tax credit for certain qualified costs incurred by a qualified apprenticeship program. Contains an unspecified sunset date. Effective 7/1/3000. (HD1)
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
HOUSE OF REPRESENTATIVES |
H.B. NO. |
1851 |
|
THIRTY-THIRD LEGISLATURE, 2026 |
|
|
|
STATE OF HAWAII |
|
|
|
|
|
|
|
|
||
|
|
||
A BILL FOR AN ACT
relating to taxation.
BE IT ENACTED BY THE LEGISLATURE OF THE STATE OF HAWAII:
SECTION 1. Chapter 235, Hawaii Revised Statutes, is amended by adding a new section to be appropriately designated and to read as follows:
"§235- Apprenticeship program income tax credit. (a) There shall be allowed to each taxpayer subject to the taxes imposed by this chapter an apprenticeship program income tax credit that shall be deductible from the taxpayer's net income tax liability, if any, imposed by this chapter for the taxable year in which the credit is properly claimed.
(b) The amount of the tax credit shall be ten per cent of the qualified costs incurred by a qualified apprenticeship program in the taxable year; provided that:
(1) The total tax credit claimed per qualified apprenticeship program shall not exceed $ per taxable year; and
(2) The aggregate amount of tax credits allowed under this section shall not exceed $ for all taxpayers in any taxable year; provided that any taxpayer who is not eligible to claim the credit in a taxable year due to the $ cap having been exceeded for that taxable year shall be eligible to claim the credit in the subsequent taxable year.
(c) If the tax credit under this section exceeds the taxpayer's income tax liability, the excess of the credit over liability may be used as a credit against the taxpayer's income tax liability in subsequent years until exhausted. All claims for the tax credit under this section, including amended claims, shall be filed on or before the end of the twelfth month following the close of the taxable year for which the credit may be claimed. Failure to comply with this provision shall constitute a waiver of the right to claim the credit.
(d) To qualify for the income tax credit, the taxpayer shall be in compliance with all applicable federal, state, and county statutes, ordinances, rules, and regulations.
(e) Every taxpayer claiming a tax credit under this section shall file with the department of taxation a written, certified statement from the department of labor and industrial relations verifying that the apprenticeship program is a qualified apprenticeship program and specifying the amount of qualified costs incurred.
(f) The director of taxation:
(1) Shall prepare any forms necessary to claim a credit under this section;
(2) May require the taxpayer to furnish information to ascertain the validity of the claim for credit made under this section; and
(3) May adopt rules under chapter 91 necessary to effectuate the purposes of this section.
(g) No taxpayer that claims a credit under this section shall claim any other credit for the same qualified costs under this chapter.
(h) As used in this section:
"Qualified apprenticeship program" means an apprenticeship program in the State that is registered and approved by the department of labor and industrial relations.
"Qualified costs" means costs directly incurred by a qualified apprenticeship program for training, instruction, and related expenses necessary to maintain program compliance and provide apprenticeship opportunities."
SECTION 2. New statutory material is underscored.
SECTION 3. This Act, upon its approval, shall apply to taxable years beginning after December 31, 2025.
|
INTRODUCED BY: |
_____________________________ |
|
|
|
Report Title:
Taxation; Apprenticeship Program Income Tax Credit; Qualified Apprenticeship Program; Qualified Costs
Description:
Establishes an apprenticeship program income tax credit for certain qualified costs incurred by a qualified apprenticeship program. Applies to taxable years beginning after 12/31/2025.
The summary description of legislation appearing on this page is for informational purposes only and is not legislation or evidence of legislative intent.
|
Date
|
Status
|
|---|---|
| Mar 12, 2026 | Referred to WAM. |
| Mar 12, 2026 | Passed First Reading. |
| Mar 12, 2026 | Received from House (Hse. Com. No. 300). |
| Mar 10, 2026 | Passed Third Reading as amended in HD 3 with none voting aye with reservations; none voting no (0) and Representative(s) Kong, Pierick excused (2). Transmitted to Senate. |
| Mar 6, 2026 | Forty-eight (48) hours notice Tuesday, 03-10-26. |
| Mar 6, 2026 | Reported from FIN (Stand. Com. Rep. No. 1160-26) as amended in HD 3, recommending passage on Third Reading. |
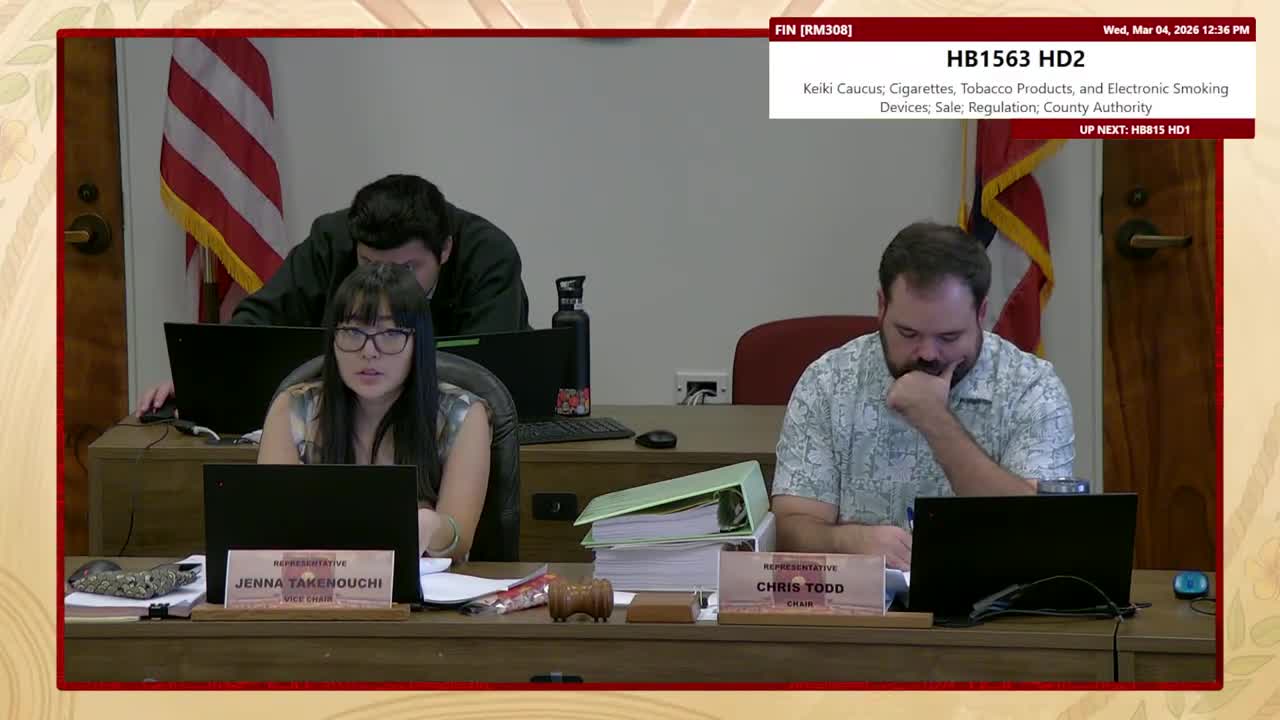
| Mar 4, 2026 | The committee on FIN recommend that the measure be PASSED, WITH AMENDMENTS. The votes were as follows: 16 Ayes: Representative(s) Todd, Takenouchi, Hartsfield, Hussey, Keohokapu-Lee Loy, Kitagawa, Kusch, Lee, M., Miyake, Morikawa, Perruso, Templo, Yamashita, Alcos, Gedeon, Reyes Oda; Ayes with reservations: none; Noes: none; and Excused: none. |
| Mar 2, 2026 | Bill scheduled to be heard by FIN on Wednesday, 03-04-26 10:00AM in House conference room 308 VIA VIDEOCONFERENCE. |
| Feb 19, 2026 | Report adopted; referred to the committee(s) on FIN as amended in HD 2 with none voting aye with reservations; none voting no (0) and none excused (0). |
| Feb 19, 2026 | Reported from ECD (Stand. Com. Rep. No. 509-26) as amended in HD 2, recommending referral to FIN. |
| Feb 13, 2026 | The committee on ECD recommend that the measure be PASSED, WITH AMENDMENTS. The votes were as follows: 7 Ayes: Representative(s) Ilagan, Hussey, Holt, Tam, Templo, Yamashita, Gedeon; Ayes with reservations: none; Noes: none; and Excused: none. |
| Feb 10, 2026 | Bill scheduled to be heard by ECD on Friday, 02-13-26 8:30AM in House conference room 423 VIA VIDEOCONFERENCE. |
| Feb 5, 2026 | Passed Second Reading as amended in HD 1 and referred to the committee(s) on ECD with none voting aye with reservations; none voting no (0) and Representative(s) Woodson excused (1). |
| Feb 5, 2026 | Reported from LAB (Stand. Com. Rep. No. 19-26) as amended in HD 1, recommending passage on Second Reading and referral to ECD. |
| Feb 3, 2026 | The committee on LAB recommend that the measure be PASSED, WITH AMENDMENTS. The votes were as follows: 6 Ayes: Representative(s) Sayama, Lee, M., Garrett, Kapela, Kong, Reyes Oda; Ayes with reservations: none; Noes: none; and Excused: none. |
| Jan 29, 2026 | Bill scheduled to be heard by LAB on Tuesday, 02-03-26 9:30AM in House conference room 309 VIA VIDEOCONFERENCE. |
| Jan 26, 2026 | Referred to LAB, ECD, FIN, referral sheet 2 |
| Jan 26, 2026 | Introduced and Pass First Reading. |
| Jan 23, 2026 | Pending introduction. |
|
Date
|
Description
|
Location
|
Votes
|
|
|---|---|---|---|---|
| Mar 10, 2026 | Third Reading | House Floor |
Passed |
|
| Mar 4, 2026 | The committee on FIN recommend that the measure be PASSED, WITH AMENDMENTS | House Standing Committee on Finance |
Passed |
|
| Feb 13, 2026 | The committee on ECD recommend that the measure be PASSED, WITH AMENDMENTS | House Standing Committee on Economic Development & Technology |
Passed |
|
| Feb 3, 2026 | The committee on LAB recommend that the measure be PASSED, WITH AMENDMENTS | House Standing Committee on Labor |
Passed |
This list shows positions taken on this bill by organizations on the date displayed, which is linked to the original source.
Positions by individuals are not included.
|
Organization
|
Position
|
Date
|
|---|---|---|
| Chamber of Commerce Hawaii | ** Support | |
| Department of Labor and Industrial Relations | ** Support | |
| Hawaii Primary Care Association | ** Support | |
| Hawaii Food Industry Association | ** Support | |
| Kohala Coast Resort Association | ** Support | |
| Maui Chamber of Commerce | ** Support |
STAND. COM. REP. NO. 1160-26
Honolulu, Hawaii
, 2026
RE: H.B. No. 1851
H.D. 3
Honorable Nadine K. Nakamura
Speaker, House of Representatives
Thirty-Third State Legislature
Regular Session of 2026
State of Hawaii
Madame:
Your Committee on Finance, to which was referred H.B. No. 1851, H.D. 2, entitled:
"A BILL FOR AN ACT RELATING TO TAXATION,"
begs leave to report as follows:
Your Committee has amended this measure by changing the aggregate cap of the tax credit to an unspecified amount.
As affirmed by the record of votes of the members of your Committee on Finance that is attached to this report, your Committee is in accord with the intent and purpose of H.B. No. 1851, H.D. 2, as amended herein, and recommends that it pass Third Reading in the form attached hereto as H.B. No. 1851, H.D. 3.
Respectfully submitted on behalf of the members of the Committee on Finance,
|
|
|
____________________________ CHRIS TODD, Chair |
|
|
|
|
STAND. COM. REP. NO. 509-26
Honolulu, Hawaii
, 2026
RE: H.B. No. 1851
H.D. 2
Honorable Nadine K. Nakamura
Speaker, House of Representatives
Thirty-Third State Legislature
Regular Session of 2026
State of Hawaii
Madame:
Your Committee on Economic Development & Technology, to which was referred H.B. No. 1851, H.D. 1, entitled:
"A BILL FOR AN ACT RELATING TO TAXATION,"
begs leave to report as follows:
Your Committee finds that apprenticeship programs provide critical workforce training and help address labor shortages in key industries. Your Committee further finds that apprenticeship programs offer an attractive opportunity for Hawaii's young workforce and can help keep young professionals in the State. However, the costs associated with supporting apprenticeships can deter employer participation. This measure encourages the expansion of apprenticeship opportunities by establishing an income tax credit to help offset qualified program costs.
Your Committee has amended this measure by:
(1) Inserting an aggregate cap for the Apprenticeship Program Income Tax Credit of $1,500,000;
(2) Inserting a sunset date of December 31, 2036; and
(3) Making technical, nonsubstantive amendments for the purposes of clarity, consistency, and style.
As affirmed by the record of votes of the members of your Committee on Economic Development & Technology that is attached to this report, your Committee is in accord with the intent and purpose of H.B. No. 1851, H.D. 1, as amended herein, and recommends that it be referred to your Committee on Finance in the form attached hereto as H.B. No. 1851, H.D. 2.
Respectfully submitted on behalf of the members of the Committee on Economic Development & Technology,
|
|
|
____________________________ GREGGOR ILAGAN, Chair |
|
|
|
|
STAND. COM. REP. NO. 19-26
Honolulu, Hawaii
, 2026
RE: H.B. No. 1851
H.D. 1
Honorable Nadine K. Nakamura
Speaker, House of Representatives
Thirty-Third State Legislature
Regular Session of 2026
State of Hawaii
Madame:
Your Committee on Labor, to which was referred H.B. No. 1851 entitled:
"A BILL FOR AN ACT RELATING TO TAXATION,"
begs leave to report as follows:
Your Committee finds that employers and training providers across the State continue to face challenges in expanding apprenticeship opportunities due to the high costs associated with program compliance, instruction, and maintaining high‑quality, industry‑aligned training. These financial barriers limit the number of apprentices who can be trained and reduce the capacity of programs to respond to workforce shortages in key sectors. This measure addresses these issues by providing a targeted income tax credit that supports qualified apprenticeship programs and helps strengthen workforce development statewide.
Your Committee has amended this measure by:
(1) Changing the tax credit amount to be $4,800 or fifty percent of the wages, whichever is less, paid to each apprentice and clarifying the definition of "qualified cost";
(2) Authorizing a taxpayer to apply the credit to the same apprentice for up to two consecutive taxable years;
(3) Inserting an unspecified sunset date;
(4) Changing the effective date to July 1, 3000, to encourage further discussion; and
(5) Making technical, nonsubstantive amendments for clarity, consistency, and style.
Your Committee respectfully requests your Committee on Economic Development & Technology, should it deliberate on this measure, to consider the following:
(1) Inserting a cap for the tax credit of $1,500,000 per taxable year;
(2) Applying the measure to taxable years beginning after December 31, 2026; and
(3) Inserting a sunset date of December 31, 2036.
As affirmed by the record of votes of the members of your Committee on Labor that is attached to this report, your Committee is in accord with the intent and purpose of H.B. No. 1851, as amended herein, and recommends that it pass Second Reading in the form attached hereto as H.B. No. 1851, H.D. 1, and be referred to your Committee on Economic Development & Technology.
Respectfully submitted on behalf of the members of the Committee on Labor,
|
|
|
____________________________ JACKSON D. SAYAMA, Chair |
|
|
|
|
|
Date
|
Testimony PDF
|
|---|---|
| Mar 4, 2026 | HB1851_HD2_TESTIMONY_FIN_03-04-26_.PDF |
| Feb 13, 2026 | HB1851_HD1_TESTIMONY_ECD_02-13-26_.PDF |
| Feb 3, 2026 | HB1851_TESTIMONY_LAB_02-03-26_.PDF |
Discussed in Hearing
 1MIN
House Standing Committee on Finance
 2MIN
House Standing Committee on Economic Development & Technology
 1MIN
House Standing Committee on Economic Development & Technology
 1MIN